When the Lawsuit Is About More Than Just the Cake and the Icing
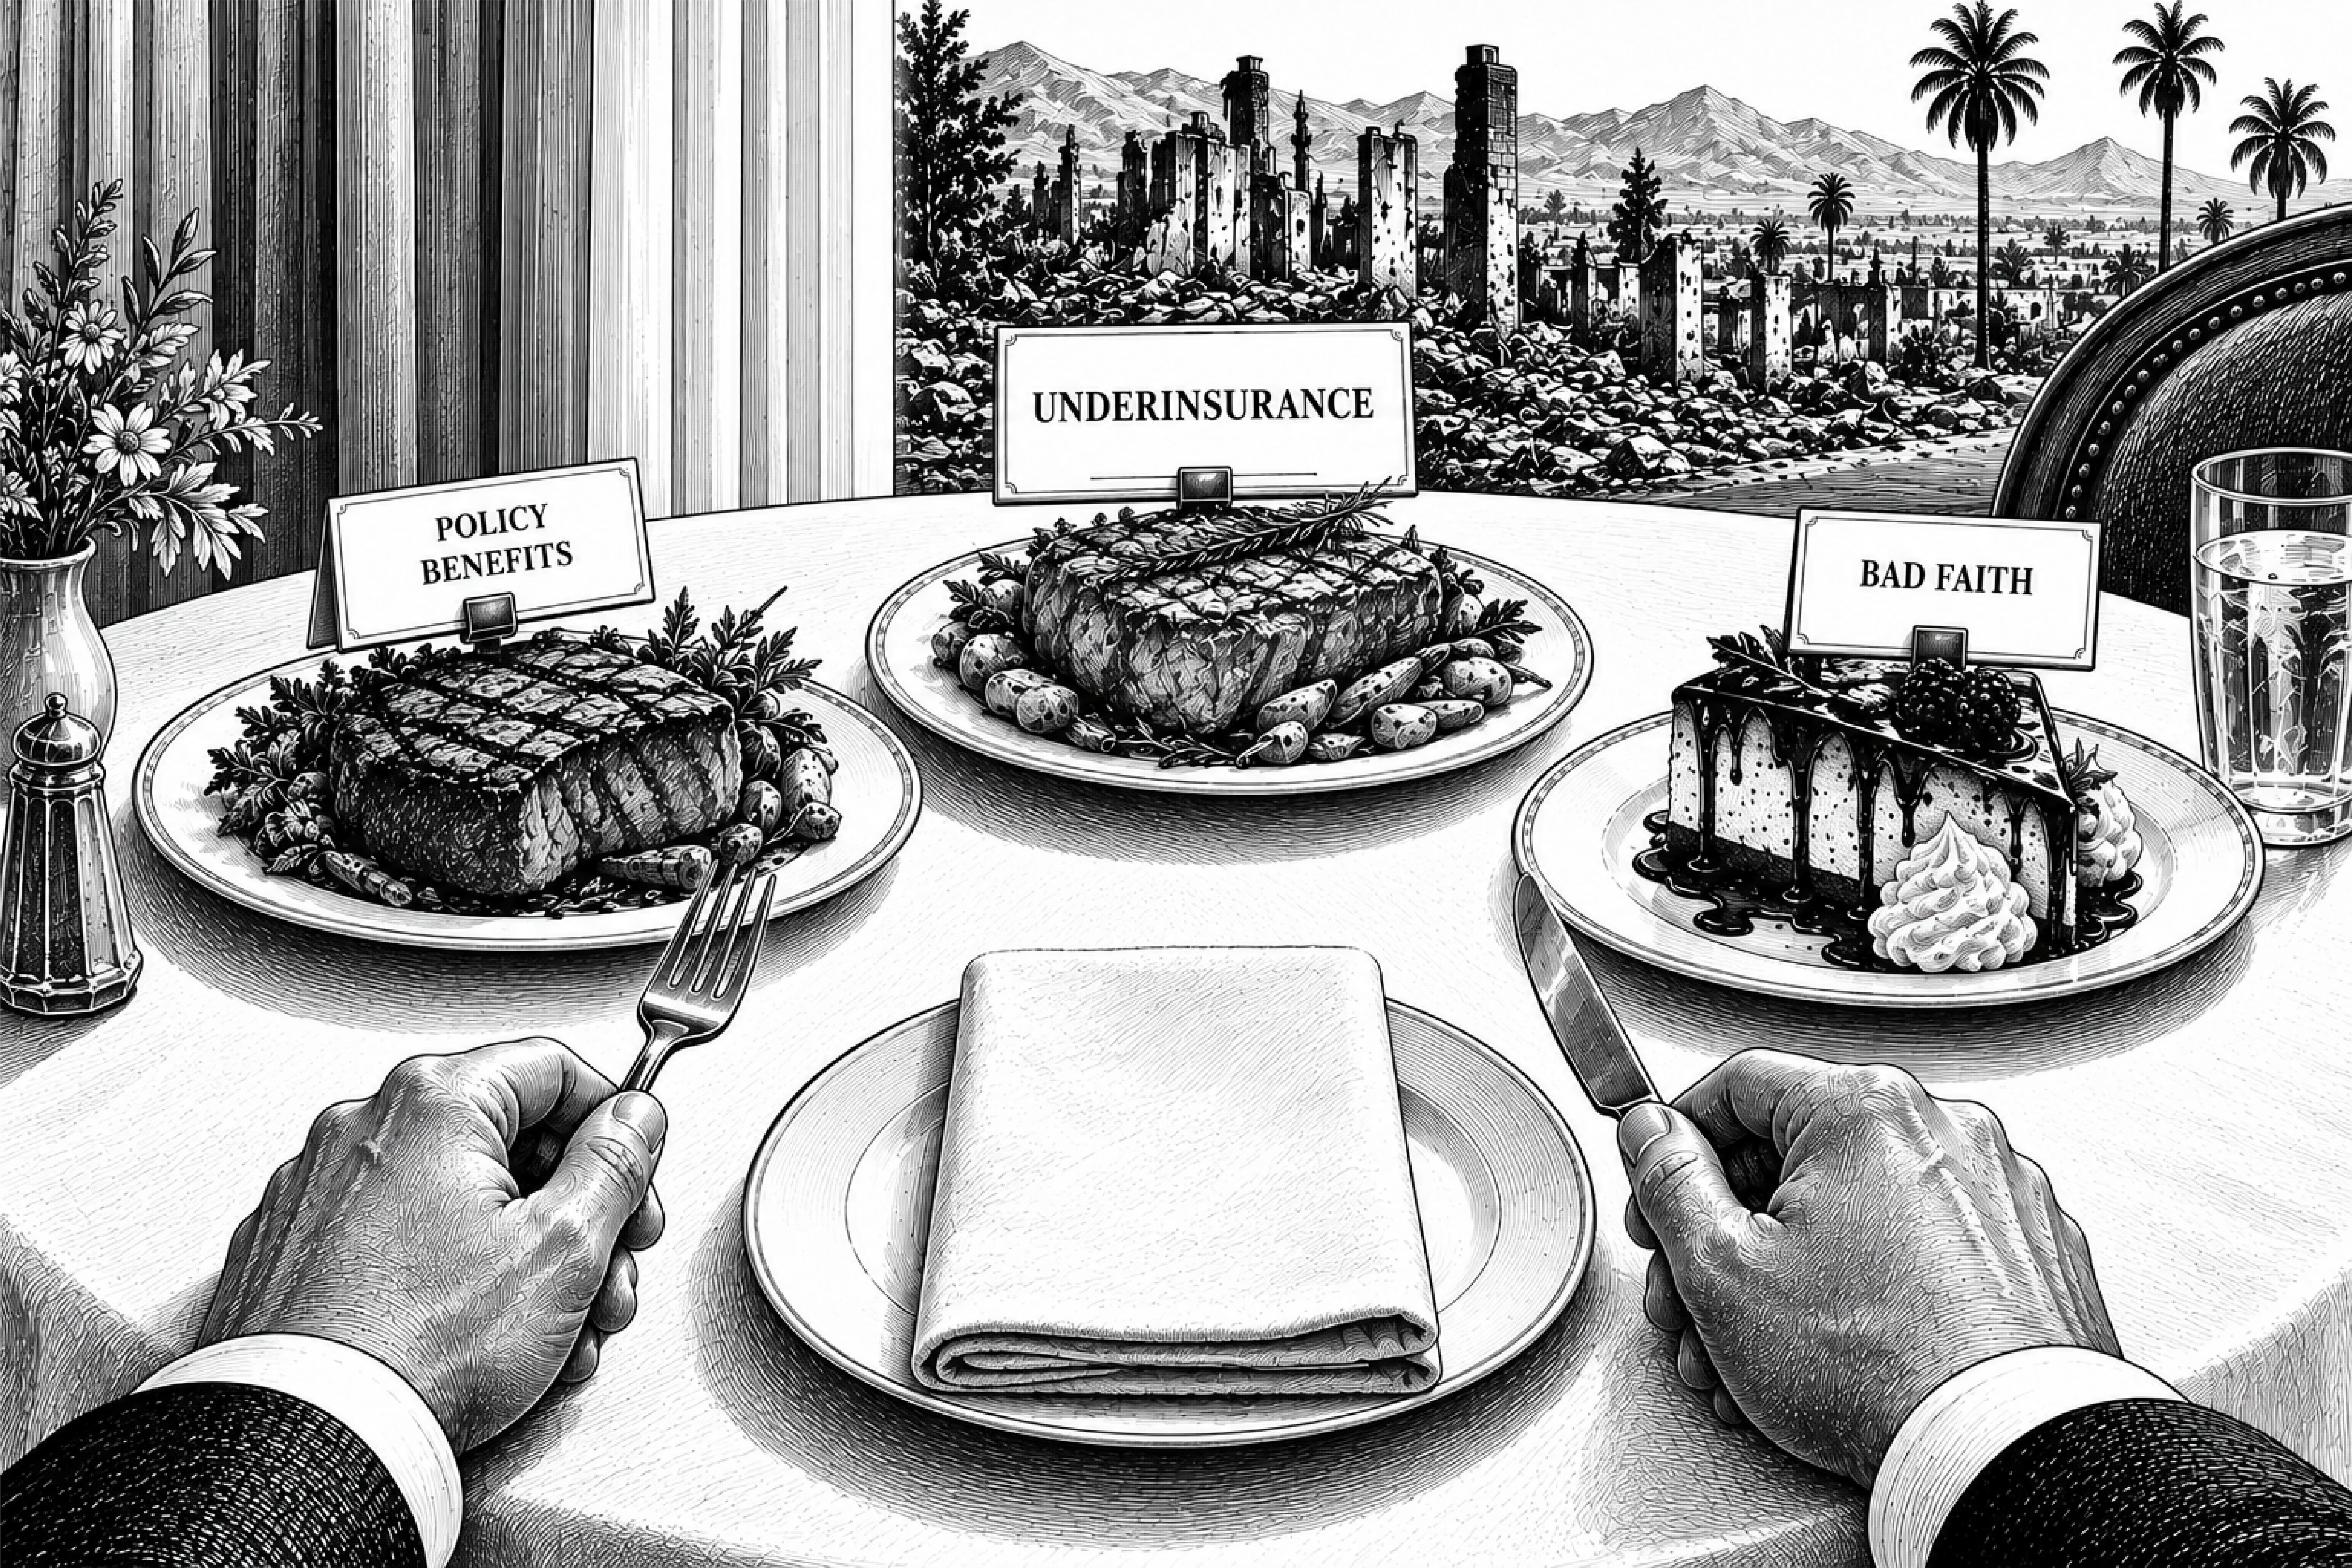
In our last Chapter, we described the benefits promised by your homeowners insurance policy as the main course and the additional damages that may be available for insurance bad faith as the desert. For many homeowners, that accurately describes a typical homeowners insurance lawsuit.
The insurance company failed to pay everything owed under the policy, handled the claim unreasonably, or both.
Sometimes, however, you discover something that may be just as damaging as the failure to pay you the policy benefits, that may become an equally important part of your lawsuit.
Think of it as a second main course.
Suppose a contractor tells you it will cost $3 million to rebuild your home. Your insurance company tells you that your dwelling coverage limit under your homeowner’s policy is only $2 million. The gap between the actual cost to rebuild your home ($3 million), and the coverage limit under your insurance ($2 million), is referred to as underinsurance. At that moment, the problem is no longer simply how to collect the full $2 million.
The problem also becomes: Why am I underinsured by at least $1 million?
That question is particularly perplexing for homeowners who purchased homeowners’ coverage known as replacement cost coverage, or even extended replacement cost coverage. The purpose of replacement cost coverage is to provide enough insurance to repair or rebuild your home after a covered loss. Extended replacement cost coverage (sometimes referred to as Option ID by California insurers), is intended to provide an additional cushion, typically 20% to 50%, to account for increased labor and material costs that commonly occur following a widespread disaster, a phenomenon known as “demand surge” or “demand surge pricing”.
If a few people in a geographic area are trying to rebuild their homes, the cost will be X because demand is low, and supply is high. If hundreds or thousands of people within the same geographic area try to rebuild their homes at the same time, the cost could be X + 20% or even as high as X + 50%, because the demand for labor and materials will often exceed the supply. That causes demand surge pricing for both labor and materials.
Think of extended replacement cost coverage as replacement cost coverage on steroids. The purpose of extended replacement cost coverage is to cover the cost to repair or rebuild your home, even in instances where demand surge pricing takes effect.
If you find yourself hundreds of thousands or even millions of dollars short after purchasing replacement cost or extended replacement cost coverages, "the breach of contract "main course" and the incurance that we discussed in the pervious and the insurance bad faith pie for desert may no longer be the whole meal. You may be entitled to a second entrée.
Unfortunately, most homeowners do not discover they are underinsured when they purchase or renew their homeowners’ insurance policy. They discover it after their home has already been damaged or destroyed. The contractor's rebuilding estimates begin to arrive. The policy limits are suddenly brought into focus. The gap between the two becomes painfully obvious. The question then becomes: If you purchased replacement cost or extended replacement cost coverage, how is it possible that you are underinsured by hundreds of thousands, or even millions of dollars?
That is a very different question from whether the insurance company handled your claim properly. Claim handling disputes focus on what happened after the loss. Underinsurance claims focus on what happened before the loss. That usually means both closely examining what occurred when you last renewed your policy, as well as what was said and done when you first purchased your homeowners insurance.
One of the first questions you should ask is surprisingly simple: Who selected the dwelling coverage limits under your policy? Did you request a specific amount? Were you given a choice? Was the subject of policy coverage limits even discussed? Did anyone show you the replacement cost estimate that was prepared before coverage limits were selected?
The answers to these and other questions will help determine if you have a potential claim against your insurance company for underinsurance. If you're like many homeowners, the answer to these and other questions may likely be "no." If so, the next logical question is: Where did those policy coverage limit numbers come from?
When a homeowners’ policy is issued, many insurance companies use software to generate an estimate of what it should cost to rebuild your home. One of the most commonly used programs is called 360Value, developed by company called Verisk. The software analyzes information about your home, its size, age, construction type, location, quality, and features, and produces what is called a replacement cost estimate. That estimate is often used as a base by the insurance company to recommend or set the dwelling coverage limit under your homeowners’ policy. The reason we refer to it as a “base” is that insurance companies usually apply a multiplier, or algorithm, or some other “secret formula” that they do not disclose publicly to the base number, in order to recommend or set you’re your dwelling coverage limit.
According to a recent San Francisco Chronicle investigation, insurers representing roughly two - thirds of the homeowners insurance market use 360Value or similar replacement cost estimating software. Like any estimate, however, the result depends on the information entered into the system and the assumptions built into the software. The concept of “garbage in, garbage out” comes to mind and accurately describes the work product generated by replacement cost software. If the information entered in the software is not correct, or if the assumptions within the software program itself are flawed, the replacement cost estimate generated by the software will not be accurate. Based upon the San Francisco Chronicle and other articles we have reviewed. there is likely way too much “garbage”, resulting in replacement cost estimates that routinely under- estimate the true cost to repair or rebuild a home.
Recent reporting, regulatory investigations, and lawsuits have raised questions about why replacement cost estimates too often substantially understate the actual cost of rebuilding a home. Among the issues identified are inaccurate property information, incomplete data, incorrect assumptions made by the software, and rebuilding costs that may not accurately reflect what contractors ultimately charge, particularly the demand surge pricing that occurs following widespread disasters.
Not surprisingly, the insurance industry disputes some of those conclusions. However, the evidence developed in litigation and regulatory investigations, has caused many homeowners and their attorneys to ask whether widespread underinsurance is the result of isolated mistakes or something more systemic. That is a question worth investigating.
If you have never seen the replacement cost estimate used to establish your dwelling coverage, ask for a copy. Find out when it was prepared.
Find out when it was last updated. Determine whether it accurately describes your home.
Small errors in the underlying information can produce very large differences in the estimated cost to rebuild your home.
The problem of widespread underinsurance is not new. Following years of complaints from homeowners after major California wildfires, the California Department of Insurance adopted regulations governing replacement cost estimates and how they are communicated to homeowners.
Those regulations were intended to improve the accuracy of replacement cost estimates and provide homeowners with better information regarding how their dwelling coverage was determined.
If replacement cost regulations were intended to reduce widespread underinsurance, it is reasonable to ask why so many homeowners continue to discover substantial coverage shortfalls after major wildfires? That question has produced criticism of both insurance companys’ failures to comply with the replacement cost estimate regulations, and the California Department of Insurance’s failure to enforcement the regulations.
For now, it is enough to understand that despite California recognizing the problem years ago and the DOI enacting specific regulations designed to solve the problem, the problem persists.
If your actual rebuilding estimate exceeds your policy coverage limit by a considerable amount, don't simply assume the shortfall was unavoidable. Find out where your policy limits came from.
Obtain every replacement cost estimate prepared when your policy was first issued and at each renewal. Compare those estimates with the actual characteristics of your home.
Those documents may become some of the most important evidence in your underinsurance case.
Depending on the facts, lawsuits involving underinsurance can be based on legal theories different from those used in claim dispute lawsuits. They frequently focus on what was said, recommended, represented, or omitted when the policy was sold or renewed, not on how the claim was handled after the fire.
One of the purposes of ISMIC is to help you become a better client. This is one example of why that matters. When you interview potential law firms, don't assume that the firm will investigate whether you were underinsured. Bring the subject up yourself. Ask whether the firm has experience evaluating or pursuing underinsurance claims and whether they are familiar with how California courts treat those claims. Ask whether the firm intends to obtain and review the replacement cost estimates prepared when your policy was issued and renewed. Ask how they determine whether an underinsurance claim exists in addition to any claims involving policy benefits or insurance bad faith. The answers will tell you a great deal about the firm's experience and how it intends to evaluate your case.
After a catastrophic loss, it is natural to focus on how your insurance company handled your claim. You should. But don't stop there. If your contractor's rebuild or repair estimate is substantially higher than the dwelling coverage limit under your homeowners’ policy, don't simply accept the difference as another consequence of the disaster. Ask why. The answer may reveal that your lawsuit involves more than recovering the cake or extra icing. You may have discovered an entirely different course of the meal.
In the next Chapter, we will focus on additional typical coverages under a homeowners’ policy and how underinsurance can impact those coverages.
In particular, we will discuss coverages on personal items lost in the fire, and what in our household became known as “The F’ing List”.
Many homeowners discover they are underinsured only after their home has been destroyed.
Underinsurance is a different issue than improper claims handling.
Claim handling disputes focus on what happened after the loss. Underinsurance claims focus on what happened before the loss.
If rebuilding costs substantially exceed your policy limits, investigate how those limits were established.
Obtain the replacement cost estimates used when your policy was issued and renewed.
California adopted replacement cost estimate regulations because underinsurance had become a recurring problem after major disasters.
Bring the subject of underinsurance up with every law firm you interview and ask about the firm's experience evaluating and litigating underinsurance claims.