For the last several Chapters, we have been building toward a final event. You filed the Complaint. The insurance company filed its Answer. You developed a discovery strategy.
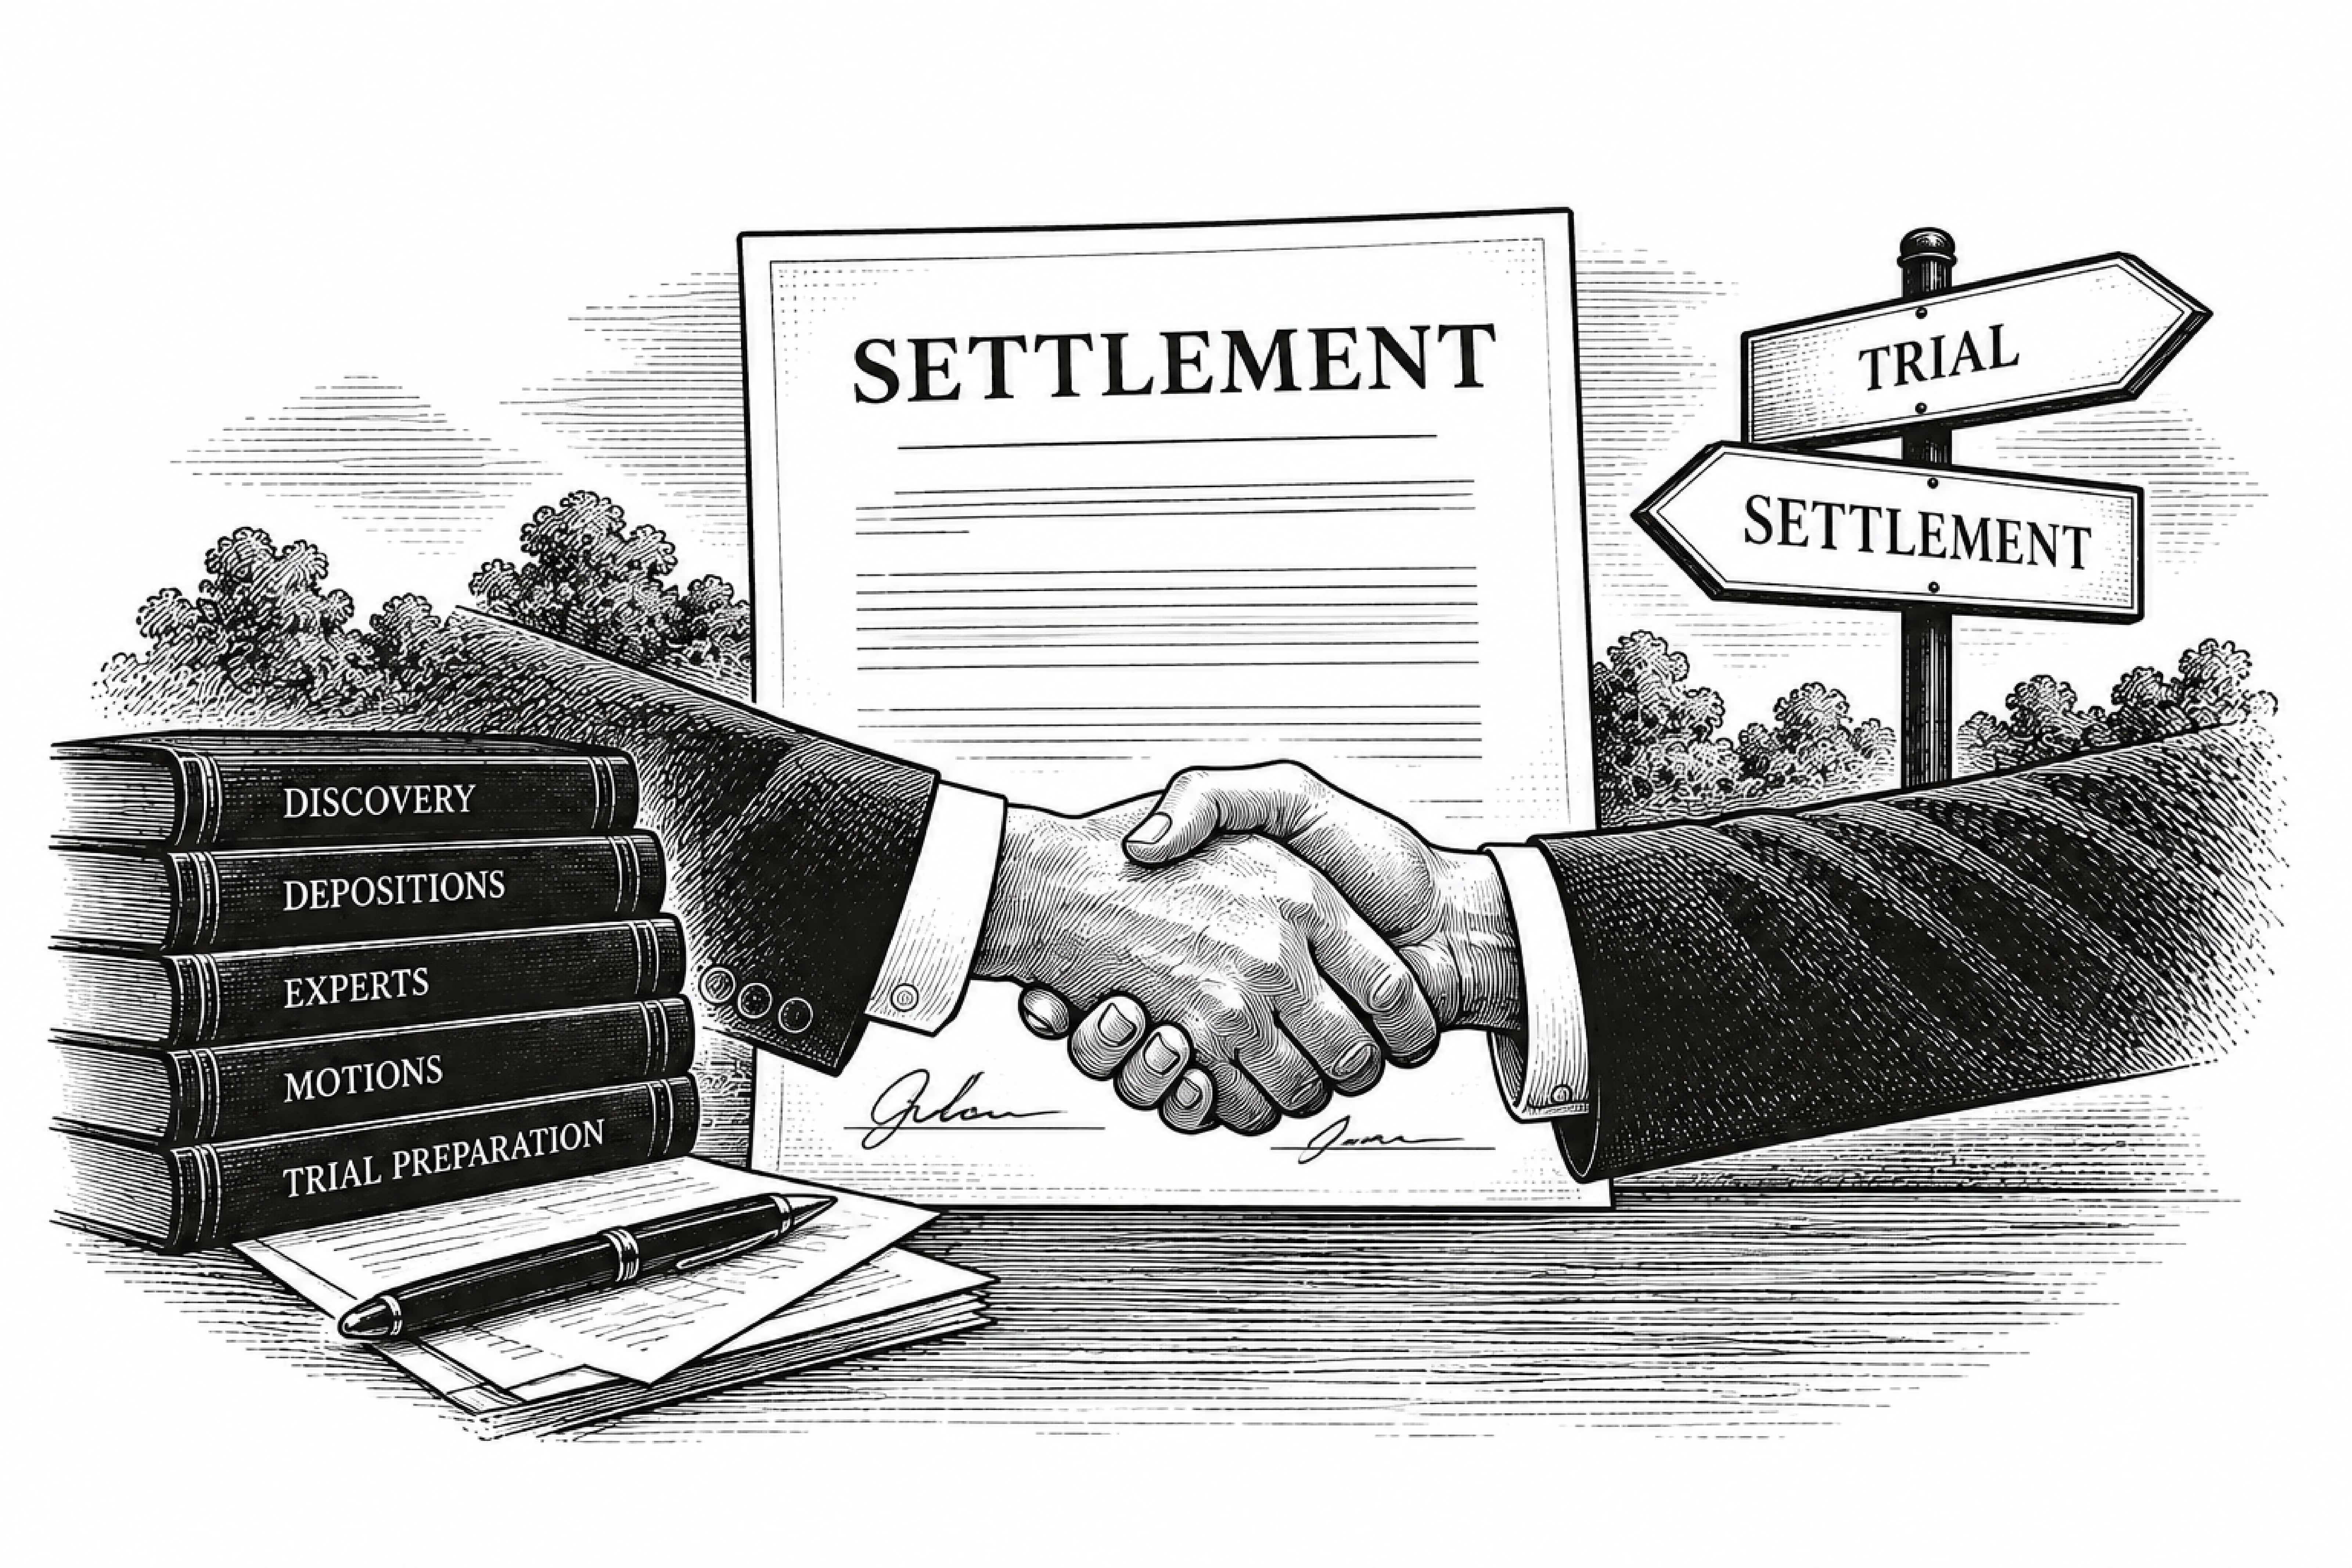
Documents were exchanged. Depositions were taken. You went to Mediation. Experts were hired. Expert discovery began. Your lawyers started getting ready for trial. The ISMIC content, and your entire lawsuit, seem to be building toward one final event.
The event that we have been building towards is not Trial. It’s SETTLEMENT. And here is why.
Of all of the insurance related lawsuits brought in U.S. Federal Courts, only one half of one percent (0.5%) ever make it to Trial. Said another way, ninety-nine and one-half percent (99.5%) of insurance related lawsuits brought in Federal Courts never make it to Trial.
There are reasons other than settlement why a case might not make it to Trial. All of the causes of action could be dismissed via Motions to Dismiss. The Plaintiff or Defendant might win or lose the lawsuit via Summary Judgment. The Plaintiff might change their mind and voluntarily request the case to be dismissed. The Court may find that the Plaintiff did not have the right to sue in the first place. There are a multitude of legal technicalities that can prevent a lawsuit from proceeding.
However, although exact statistics are not available, the number one reason why cases do not make it to Trial is because they settle. Academic studies suggest that settlement occurs in approximately 60% to 70% of civil lawsuits.
In the almost forty (40) years that I have been managing complex civil lawsuits, I have never had a case make it to Trial. Not once. The closest I got was the day before Trial, at which time the lawsuit settled.
If so few lawsuits ever make it to Trial, and such a large percentage of lawsuits end with a settlement, why do we spend so much time covering Trial related activities?
The answer is a two-part answer. Number 1, parties that have a dispute often use the framework and rules governing a lawsuit, and in particular the Complaint, Answer, Motions to Dismiss, Discovery, Depositions, Expert Discovery, and Motions for Summary Judgment, as the vehicle to get all of the facts out into the open and all of the legal theories on the table, so that the parties can accurately assess the merits of their case, and their relative risks.
Number 2, the threat of going to Trial serves as incentive to push the parties towards a settlement. For Plaintiffs, particularly Plaintiffs that have no lawsuit experience, potentially going to Trial is a frightening proposition. For Defendants, particularly corporate Defendants, going to Trial can be very risky, and an adverse verdict can have consequences well beyond that particular lawsuit. And for both Plaintiffs and Defendants, taking a case all the way to Trial is prohibitively expensive.
Are there more efficient, less expensive, better ways to resolve disputes than using rules and procedures of the legal system to drive settlements? Some people think “yes” and prefer alternative dispute resolution forums like binding arbitration. Others think “no,” and that it is the high costs of litigation, and the high risks and unpredictability of lawsuits, that are the causes of so many settlements.
For you, once the insurance company has made it clear that it is not going to voluntarily pay everything you believe you are owed, your choices may be limited. You can accept what the insurance company is willing to pay, or you can file a lawsuit and use the rules and procedures of the legal system to try to obtain more.
Filing a lawsuit does not mean that you expect to go to Trial.
Settlement should not be something that suddenly appears on the agenda when somebody suggests Mediation, or happens to bring it up. It should be part of your lawsuit strategy from the beginning.
That does not mean you should be trying to settle your lawsuit from the day you file it. Sometimes the worst time to approach settlement is early in the case, before you have developed the evidence necessary to demonstrate its value.
Settlement strategy means something different. From the beginning, you and your legal team should be thinking about what needs to happen to create opportunities to settle the case on acceptable terms. What facts do you need to establish? What documents do you need? Whose deposition could materially change the insurance company's view of the case? What does the insurance company need to learn before it can realistically evaluate its exposure? What events are likely to increase your leverage? And when those events occur, should you try to convert that leverage into a settlement?
Don't just wait for settlement opportunities to occur out of thin air. Look for ways to create them.
Before you can decide whether a settlement is good enough, it helps to remember why you brought the lawsuit in the first place.
Was it to get what the insurance company promised you? To be made whole? To recover the additional damages caused by the insurance company's conduct? To be compensated for what you went through? Or was part of your motivation to punish the insurance company for the way it treated you?
That last one requires some special thought.
Within the confines of a lawsuit, damages awarded to punish a Defendant are called Punitive Damages. Punitive Damages can sound very attractive. If the evidence supports them, the possibility that a jury could award Punitive Damages may also create significant settlement leverage. But the bar to qualify for Punitive Damages is set very high, and the probability of being awarded punitive damages is fairly low.
However, there is an important difference between Trial and Settlement. At Trial, you can ask a jury to punish the insurance company. In a Settlement, you are asking the insurance company to voluntarily punish itself. No Defendant, particularly a multimillion or multibillion-dollar insurance company, is likely to agree that it deserves to be punished and then volunteer an amount of money that that contains Punitive Damages.
That doesn't mean punitive damages are irrelevant to settlement. Far from it. The risk of punitive damages can be used as settlement leverage. The insurance company may be willing to pay substantially more to eliminate the risk that a jury will punish it. But from the insurance company's perspective, that is still a business decision.
Remember something we discussed earlier in this Series: despite how personal the insurance company's conduct may feel to you, to the insurance company it is, for the most part, strictly business. Settlement is a time when you may need to bring some of that same economic discipline to your own decision-making.
Picture your lawsuit as a seesaw. When the lawsuit begins, neither side knows exactly where it will end up. Then things start happening. You uncover a helpful document. Your side goes up. An important witness gives a great deposition. It goes up even higher. The judge makes an unfavorable ruling. Your side goes down. The insurance company's witness gives testimony that helps your case. You go up again. Your expert identifies a problem you hadn't anticipated. Down you go. You survive a potentially case-ending motion. You go up to the top.
Leverage moves back and forth throughout a lawsuit. And it isn't only your position on the seesaw that matters. Momentum matters too.
You may not yet be clearly up, but if events are moving rapidly in your direction, the insurance company can see that just as clearly as you can. That can create a settlement opportunity.
As a general strategy, you would rather explore settlement when the seesaw is level, tilted in your direction, or moving in your direction than immediately after events have moved against you.
The goal isn't simply to accumulate leverage. At some point, you need to convert leverage into an outcome. And the outcome you are looking for is a positive settlement.
There is no single right time. But there are natural points during a lawsuit when you and your legal team should ask whether it makes sense to explore settlement.
One particularly interesting point may occur after significant fact discovery but before substantial expert discovery and final trial preparation. By then, much more is known.
Documents have been exchanged. Important witnesses may have been deposed. Both sides have a much better understanding of the strengths and weaknesses of the case.
At the same time, a very expensive and time-consuming part of the lawsuit is about to begin. Experts need to be hired. They need to review the evidence. Opinions need to be developed. Expert depositions need to be taken. Lawyers need to start to prepare the case for Trial.
That can create an attractive window. The case may be mature enough to value without having incurred all of the expense required to take it the rest of the way. That doesn't mean you should always settle before expert discovery. Sometimes expert discovery creates the leverage necessary to obtain the settlement you want.
The larger point is this: before entering another expensive stage of the lawsuit, ask whether this is a good time to explore settlement.
This distinction is critical. Suppose you and your lawyers believe a jury could award you $10 million. Does that mean your lawsuit has a settlement value of $10 million?
Of course not. You might lose. The jury might award substantially less. The Judge could make an unfavorable evidentiary ruling. An important witness might not perform as expected. An expert could be excluded. Even after you win, there could be post-trial motions or an appeal. And continuing the lawsuit requires more money, more time and more of your attention.
Settlement replaces many of those uncertainties with certainty. That certainly has value.
So when evaluating a settlement offer, don't simply compare the offer with the largest verdict you believe you could possibly obtain. The better question is: How does this offer compare with the realistic, risk-adjusted alternatives if I continue?
The insurance company is performing its own version of exactly the same calculation.
Settlement happens when those calculations get close enough to produce an agreement.
Not necessarily. Some Plaintiffs worry that merely suggesting settlement tells the insurance company that they are worried about their case or desperate to get out. Context matters. If something terrible has just happened to your case and you immediately ask whether the insurance company wants to settle, the timing may send a message. But suppose you just uncovered important evidence. Or took an excellent deposition. Or survived an important motion. The seesaw is moving your way. Approaching settlement at that moment may not demonstrate weakness at all. It may be an attempt to capitalize on strength.
The objective isn't to prove that you are tougher than the insurance company. The objective is to obtain the best reasonable result.
What happens if you try to settle and it doesn't work? You keep going. And you can try again. A failed settlement discussion does not mean the parties can never talk again. You can exchange settlement offers, fail to reach an agreement, return to the lawsuit and resume settlement discussions later.
In fact, calling the first discussion a failure may miss the point. Every time you try to settle, you learn something. You may learn how the insurance company currently values the case. You may learn which parts of your case concern it most. You may learn which arguments aren't moving it. You may learn whether the person across the table has meaningful settlement authority. You may learn how large the gap actually is. And the insurance company learns things about you.
Then you return to the lawsuit. More documents are produced. More depositions are taken. Motions are decided. Experts weigh in. Trial gets closer. The seesaw moves again.
Six months later, the case may look very different to both sides. And when you sit down again, you aren't repeating the first negotiation. You are beginning the next negotiation with more information.
Settlement negotiations can be cumulative. The negotiation that doesn't produce a settlement today may help produce the settlement six months from now.
Before serious settlement negotiations begin, you should have spent time with your lawyers thinking about the value of your lawsuit and the settlement value of your lawsuit. Not just one number. What is the realistic range of outcomes at Trial? What are the significant risks? What would constitute an exceptional settlement? What would constitute a very good settlement? What would constitute an acceptable settlement? And at what point would you rather continue the lawsuit than accept the amount being offered?
Those answers aren't carved in stone. As the evidence changes, the numbers may change. When the seesaw moves, your evaluation should move with it.
ISMIC has spent a lot of time encouraging you to become a Better Client. Don't sit on the sidelines. Learn your case. Understand the strategy. Help your lawyers. Prepare. Ask questions. Participate. That involvement can help you and your legal team build a stronger case. And a stronger case can create a better settlement opportunity. But there is another skill that is very important to being a better client.
You need to recognize a good settlement opportunity and a good settlement offer, when it arrives. That isn't always easy. By the time a serious settlement offer arrives, you may have been fighting your insurance company for months. You know every argument. You remember every slight. You have lived through discovery disputes, depositions, motions and Mediation. You may be winning. And that can make it surprisingly difficult to stop.
You need to recognize a good settlement opportunity and a good settlement offer, when it arrives.
You may look at a very good offer and think: If they're offering this much now, imagine how much more we can get if we keep going. Maybe you can. But maybe the reason the offer
is so good is because the seesaw is currently tilted in your direction. There is no guarantee it will stay there. Leverage has value only if you eventually convert it into an outcome.
And most of the time, that outcome is a settlement.
This is something you should consider doing before a serious settlement offer arrives. Identify someone you trust, with good judgment, who can help you evaluate whether it is time to stop fighting. We'll call that person your Settlement Safe Person.
It might be your lawyer. It might be another trusted member of your legal team. It might be your spouse or significant other. It could be another trusted advisor.
The important thing is that the person understands what you are trying to accomplish but has enough distance from the daily battle to see things that may be difficult for you to see while you are in the heat of the battle.
And give that person permission to tell you something you may not want to hear. The ultimate decision of whether to accept a settlement offer continues to be your decision. Your Settlement Safe Person's job isn't to make that decision for you. It is to help you ask yourself a very important question: Am I rejecting this offer because continuing the lawsuit is objectively the better decision, or because I am not ready to stop fighting?
Settlement buys something else. An ending. Lawsuits take time. They demand attention. They occupy mental space. As you now know, when you are a Better Client you don't simply hand your lawsuit to your legal team and forget about it. You participate. You do independent research. You direct. You take an active role. You lead the team. That participation can help create the settlement opportunity you have been working towards. But it can also become addicting. You can become addicted to the adrenaline of the fight.
And you may even like it.
But the objective isn't to keep fighting forever. At some point, you may receive an offer that fairly compensates you, appropriately reflects the risks of continuing, and gives you the opportunity to put the lawsuit behind you. It may not be everything you once hoped to receive. It may not punish the insurance company the way you believe it deserves to be punished. It may even be less than you believe a jury could award you. And it still may be a very good settlement. This is where your Settlement Safe Person can help.
There is value in certainty. There is value in eliminating risk. There is value in getting your time back. And there is value in being able to move on with your life.
We spent much of this series preparing you for Trial. There was a reason for that. Your lawyers need to be prepared to go to Trial. The insurance company needs to believe that you are willing to go to Trial. And if settlement doesn't happen, you may actually have to go to Trial (although as we have discussed, the chances are low).
Trial preparation creates leverage. But going to Trial isn't the objective. The objective is a good result and is the vast majority of lawsuits that result is achieved via Settlement. For the overwhelming majority of Plaintiffs, the curtain will never rise on a Trial. Their Grand Performance will happen somewhere else. Perhaps in a Mediation. Perhaps during a telephone call between lawyers. Perhaps after an important deposition. Perhaps after the Judge rules on a motion. Perhaps six months after everyone walked away from a Mediation convinced the case couldn't settle.
The Professional Client prepares for Trial. The Professional Client creates opportunities for Settlement. One of the hardest things a Professional Client needs to learn, is how to recognize a good settlement offer from a bad settlement offer. And that takes us back to why
you filed the lawsuit in the first place. Think back to when you decided to sue your insurance company. If you were offered then, what the settlement offer is now, would you have taken it? What has changed between then and now? Has your case gotten worse, or better? Have you accomplished what you set out to do? Why, or why not? These are some of the questions that you should think about and discuss with your Settlement Safe Person.
Every performance has an ending. It might not be a perfect ending, but is it an ending you can live with? At some point the curtain must come down. It is far better for that to happen after you have taken your bow and stepped off stage, than when you are at the front of the stage and still trying to perform your lines.
Every performance has an ending. It might not be a perfect ending, but is it an ending you can live with?
Prepare for trial from Day One. Plan for settlement from Day One.
In U.S. Federal, only about one-half of one percent of federal insurance cases make it to trial.
Settlement should be a strategy, not merely an event that occurs at mediation.
Create settlement opportunities. Don't just wait for them.
Think of leverage as a seesaw . Look for settlement opportunities when you are even, up, or moving upward.
Before entering another expensive stage of the lawsuit, consider whether it is a good time to explore settlement.
Trial value and settlement value are not the same thing.
Punitive damages may create settlement leverage, but don't expect the insurance company to voluntarily agree to be punished.
Raising settlement first is not necessarily a sign of weakness. Timing and leverage matter.
You can try to settle more than once. Every settlement discussion teaches you something.
Know your settlement numbers before you need them, and reevaluate them as the lawsuit changes.
Creating a good settlement opportunity is only half the job. You also have to recognize it.
Identify a Settlement Safe Person who can help you evaluate an offer when you are in the heat of the battle.
There is real value in certainty, ending the fight and getting the lawsuit out of your life.
Leverage has value only if you eventually convert it into an outcome.
The Professional Client knows how to fight. The Professional Client also knows when it makes sense to stop.