Decide What Type of Fee Arrangement Best Meets Your Financial Needs
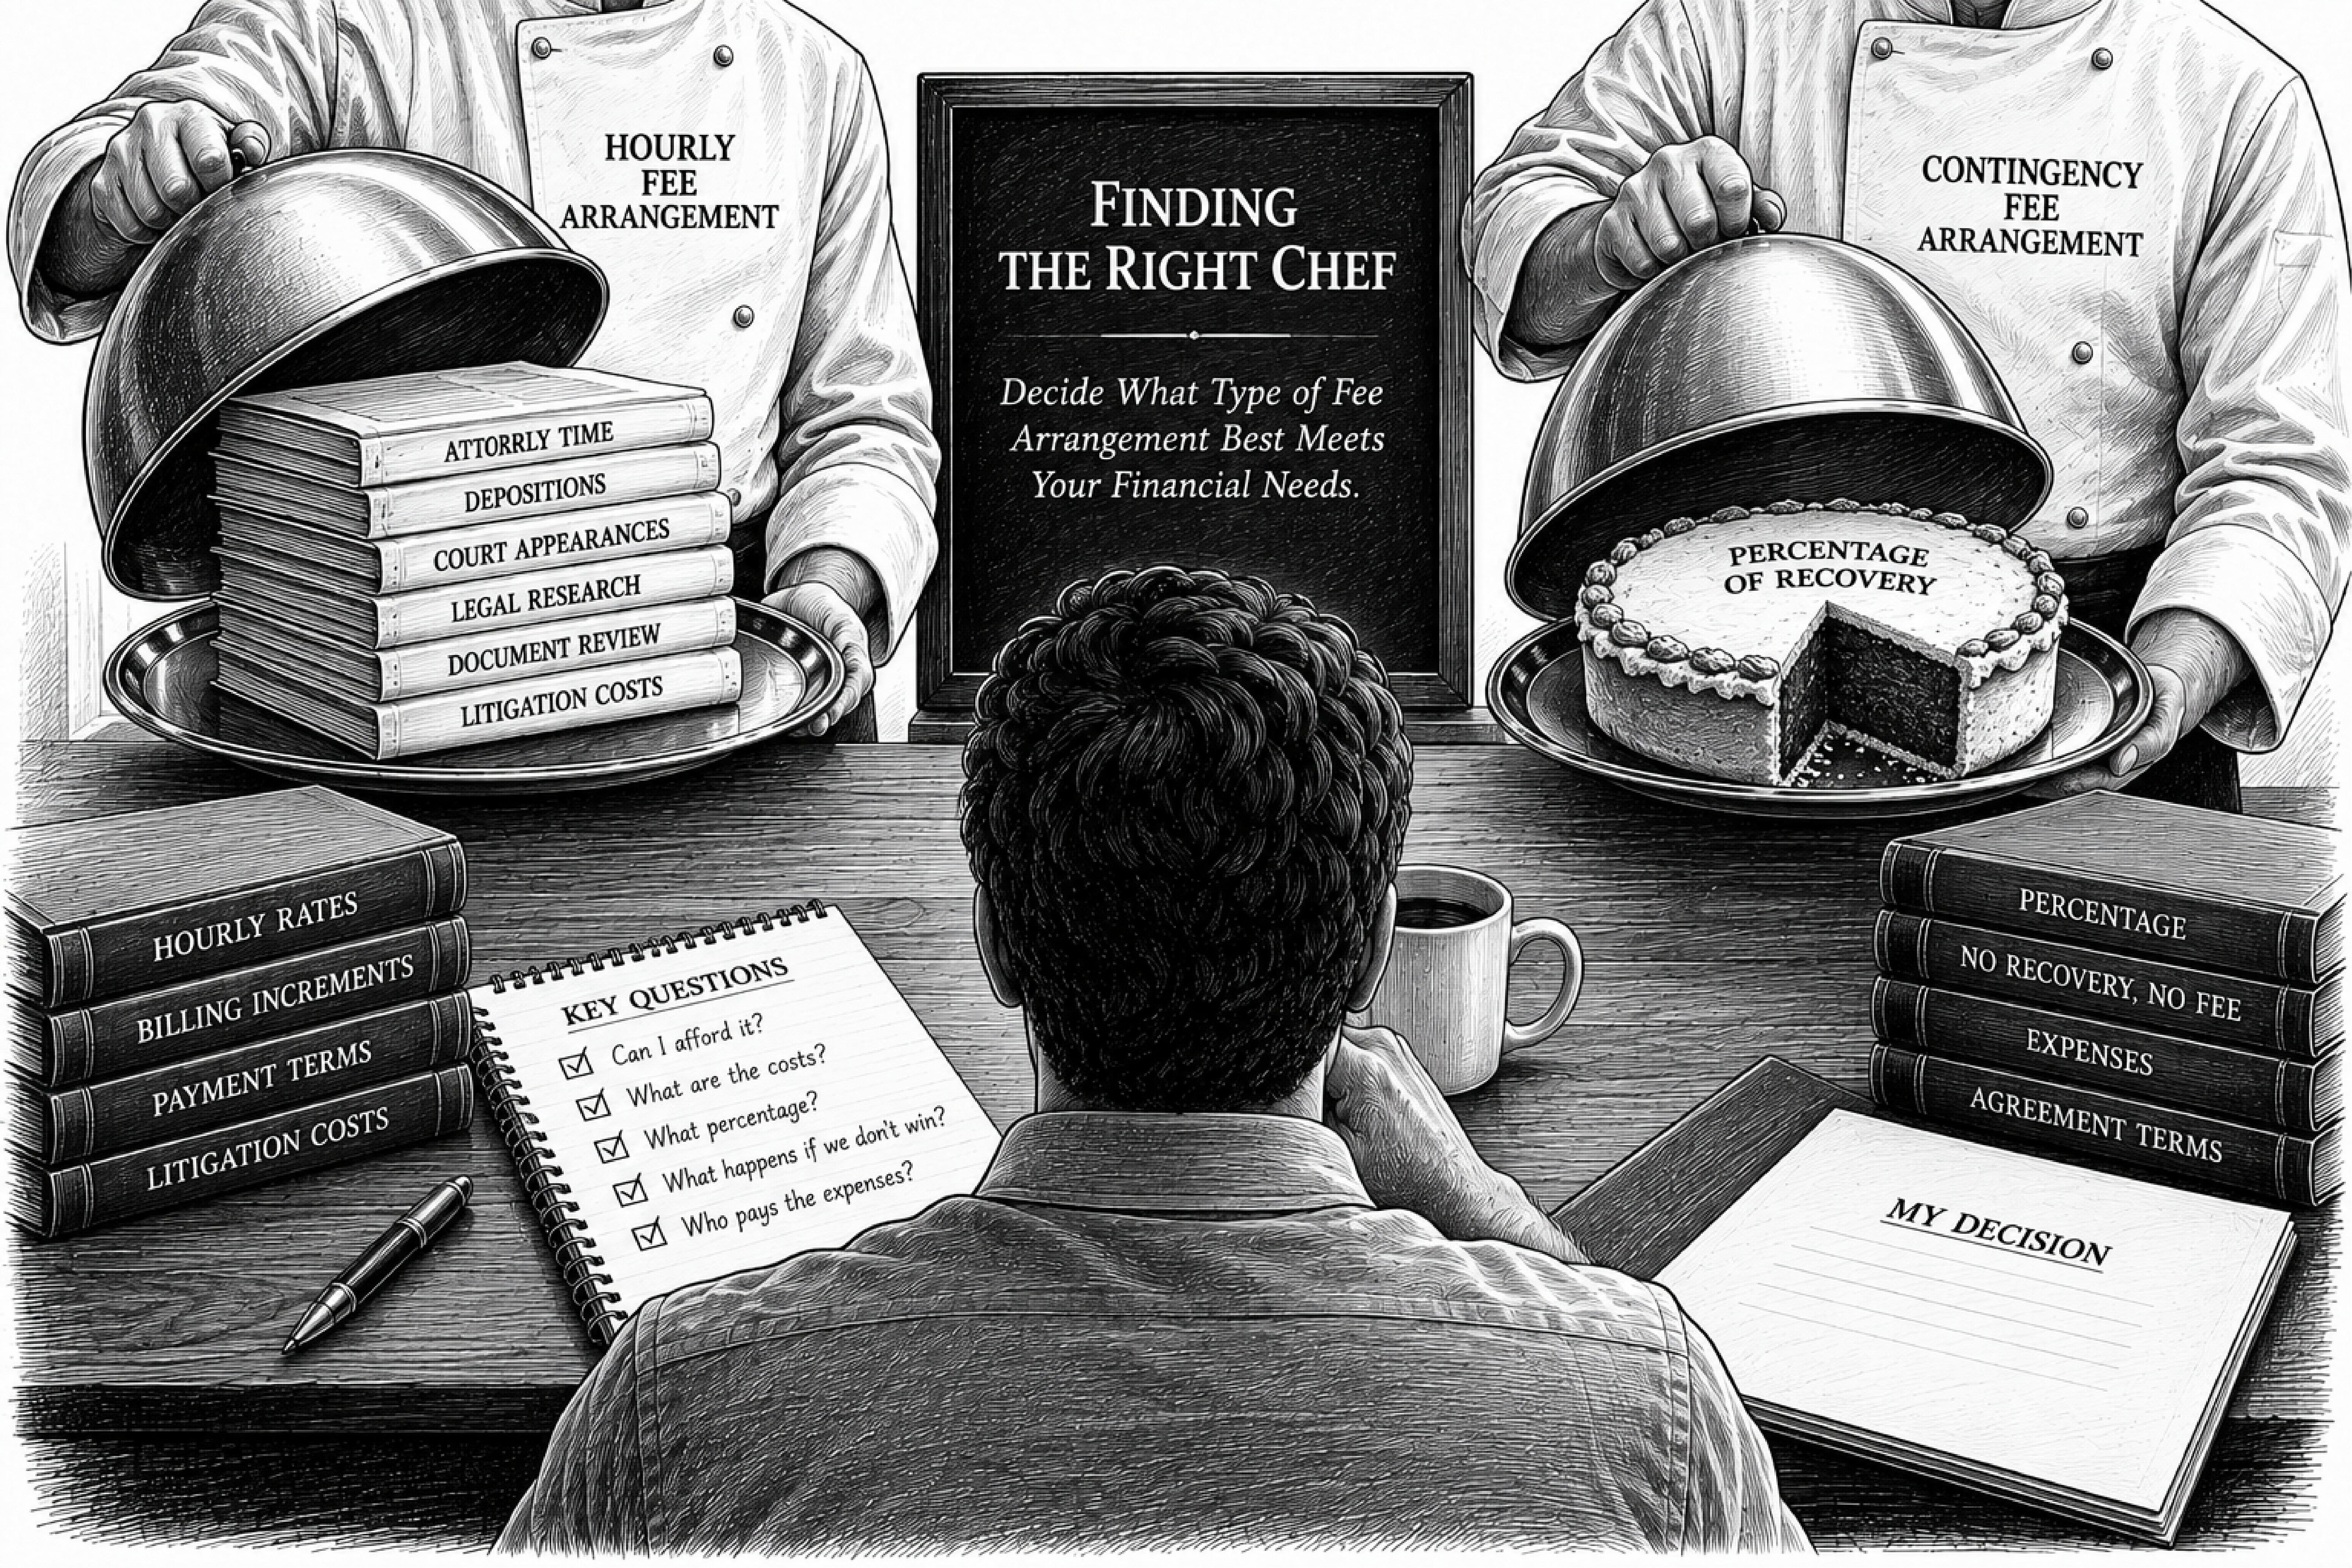
Before you begin interviewing lawyers, you should first decide what type of fee arrangement best meets your financial needs. For most homeowners considering a lawsuit against their insurance company,
the first question is not, "Which lawyer or law firm should I hire?" It is, "How am I going to pay for this lawsuit?"
The answer to that question depends largely on the way a law firm bills for its services. Litigation law firms generally subscribe to one of two primary fee arrangements: hourly billing, and contingency fees. An important first step is understanding the difference between those fee arrangements, as well as who will be responsible for outside costs that are incurred along the way.
An hourly fee arrangement is one in which a law firm bills you for the time that is spent working on your case. Time is billed at the hourly rate for the attorney or paralegal that is working on your case. Hourly rates can be as low as a few hundred dollars an hour (e.g. paralegal) to over $1,000 per hour, depending on the experience of the attorney. The more the experience, the higher the hourly rate. Time is generally billed in 6-minute or 15-minute increments and should be billed contemporaneously as the services are being performed. At the end of each month, you should receive a detailed bill where each time entry describes the amount of time spent, the name of the attorney that billed the time, and a detailed description of what the attorney did during that time period. In addition to each individual entry, the bill should provide a total for the time that each attorney spent working on your case during that month. Payment terms can vary, but payment to the law firm is most often due within 30 days.
Under an hourly fee arrangement, the client pays for the attorney's time spent working on the case, whether the lawsuit ultimately succeeds or not.
Every telephone call, meeting, deposition, court appearance, document review, legal research project, motion, and trial preparation activity is typically billed based upon the amount of time required to perform the work. In addition to partner attorneys, you may also be billed for work performed by associates, paralegals, law clerks, litigation support personnel, and other professionals working on the case.
Litigation costs, including third party and other outside expenses incurred by the law firm, are generally billed separately. Those costs may include filing fees, court reporters, deposition transcripts, expert witnesses, document management systems, trial exhibits, travel, and many other expenses incurred while preparing the case.
The main advantage of an hourly fee arrangement is the client keeps 100% of any recovery from the lawsuit. The law firm receives payment of their hourly fees, regardless of whether the lawsuit is successful or not and the full settlement or judgment goes to the client.
The main advantage of an hourly fee arrangement is the client keeps 100% of any recovery from the lawsuit.
The main disadvantage of an hourly fee arrangement is equally obvious. Complex insurance lawsuits require a lot of attorney time. Unless the case settles early, attorney's fees and litigation costs can become substantial. The amount of time required to prepare a lawsuit for trial depends upon many factors, including the complexity of the issues, the amount of discovery required, the number of depositions taken, and the number of experts retained.
Based upon our experience, if you engage a law firm that bills on an hourly basis for a homeowners’ insurance lawsuit, you should expect to incur between $500,000 and $1,000,000 in attorney's fees, not including the attorney’s fees and costs incurred during the trial.
Let’s look at an example of the economics for an hourly fee arrangement. Assume that you file a lawsuit and after 6 months, your lawsuit settles for $3,000,000. Over that 6 months period, you paid $400,000 in hourly legal fees and $50,000 of costs. In that scenario, you keep the entire $3,000,000, and your net gain after legal fees and costs is ($3,000,000 - $400,000 – $50,000) is $2,550,000.
In a contingency fee arrangement, the law firm takes a percentage of the proceeds recovered in a lawsuit, if any, instead of being paid hourly fees.
Instead of billing you for every hour worked, the law firm receives an agreed percentage of the settlement or judgment. If there is no recovery, the
law firm generally does not receive a fee for the time invested in the lawsuit.
Depending upon your financial resources, a contingency fee arrangement may be the only practical way to pursue a lawsuit against your insurance company.
Contingency fee agreements, however, are not all the same.
One of the first questions you should ask a potential contingency firm is what percentage of the recovery the law firm will receive. Although percentages vary, contingency fee agreements commonly provide for attorney's fees ranging from approximately one-third (33%) to forty percent (40%) of the recovery.
Litigation Costs are Separate from Attorney's Fees.
As discussed above, litigation costs may include filing fees, court reporters, deposition transcripts, expert witnesses, insurance experts, construction experts, economists, electronic document management, trial exhibits, travel, and many other expenses incurred while preparing the case. Depending upon the complexity of the lawsuit, those costs can easily reach tens of thousands of dollars. In complex cases that proceed through trial, litigation costs may reach well into six figures.
Another important question is who is responsible for paying the litigation costs while the lawsuit is pending. Some contingency fee agreements require the client to pay litigation costs as they are incurred. Others provide that the law firm will advance those costs and recover them from any settlement or judgment. Still others use a combination of both approaches.
You should also understand how litigation costs and attorney's fees will be calculated if your lawsuit is successful. Many contingency fee agreements provide that litigation costs advanced by the law firm are first reimbursed from the client’s portion of the proceeds. Other fee agreements may use a different method. Before signing any fee agreement, make sure you understand exactly how attorney's fees and litigation costs will be calculated.
Let’s look at the example we used above, assuming that you hired a law firm that works on contingency, with a 35% contingency percentage and with the law firm advancing the costs.
The case settles for $3,000,000. The law firm’s fee, based upon gross recoveries is $1,050,000 (35% x 3,000,000). As the client, you end up with $1,900,000 ($3,000,000 (gross recovery) - $1,050,000 (attorney’s contingency fee) – $50,000 (costs)).
Under the hourly billing fee arrangement, you ended up with $2,550,000 and under the contingency arrangement you ended up with $1,900,000, $650,000 less than the hourly fee arrangement. In this example, the law firm receives a larger fee, and you receive a smaller net recovery, because the law firm assumed the risk that it might never be paid and advanced the litigation costs throughout the lawsuit.
Before you get too excited about hourly fee billing arrangements, keep in mind that the longer the lawsuit continues, the more legal fees and costs you are funding out of pocket. And whether you can continue to fund those fees and costs may impact your settlement posture for the lawsuit.
As a rule of thumb, I would say that unless you have approximately $2,000,000 that you can set aside and use to fund the attorney fees and costs through trial, you are probably better off seeking a law firm that works on contingency. If, in a worst-case scenario, you can afford to lose the $2,000,000 (if you don’t settle or prevail in the lawsuit), an hourly fee arrangement may make more sense for you.
When a law firm accepts your case on contingency, they will generally conduct more due diligence than a law firm that bills hourly. For that reason, even if you can afford an hourly fee arrangement, it may make sense to talk to some contingency law firms as well. Since a contingency firm is betting on the success (or failure) of your lawsuit, it may be helpful to see how they assess your case (compared to a non-contingency firm, that gets paid hourly) and whether they will accept the case on contingency.
It is important to understand how attorney's fees and litigation costs work, and whether an hourly fee arrangement is even a financial possibility for you, before seeking out law firms to handle your case. If you can’t afford an hourly billing arrangement, you should limit your focus to law firms that take contingency cases. If you can afford to pay hourly fees, you probably want to consider both contingency and hourly law firms.
Throughout this series of Chapters, we have addressed topics from the perspective of a client and have tried very hard to not sound like a lawyer.
However, to answer the question of whether you are entitled to recover your attorneys’ fees if you sue your insurance company, we need to give you a lawyers’ answer: “It depends”.
Under California law, attorneys’ fees spent to recover amounts owed under the policy (commonly referred to as “Brandt Fees”) are generally recoverable, if you win at trial. The issue becomes what is and is not “owed under the policy”. For example, let’s assume the cost to rebuild your home is $4,500,000, the dwelling coverage limit under your policy is, $3,000,000, your insurance company only pays you $2,000,000, and you elect to bring a lawsuit. Legal fees spent to collect the additional $1,000,000 that you are owed under the policy would be recoverable if you win at trial.
But in the example above, it appears that you are underinsured by $1,500,000. Legal fees spent to collect the $1,500,000 of underinsurance may not be recoverable. Your attorney would argue that because you purchased extended replacement cost coverage, and the purpose of replacement cost coverage is to cover the full cost to rebuild your home, the $1,500,000 is a benefit of the policy, regardless of the policy’s coverage limit. The insurer will argue that the coverage limit is what you are owed under the policy, and for anything exceeding that amount you are not entitled to recover attorneys’ fees. Your insurance company may have the better argument, but the law is not definitive enough to where you should concede the issue.
We already introduced you to other types of potential damages such as insurance bad faith. We will continue the damages topic later in the next series, when we introduce other potential recoveries such as emotional distress, physical sickness, and interest. While attorneys’ fees for these types of damages are not recoverable as Brandt fees, they may be recoverable under other California law.
Finally, do you recover attorneys’ fees if you elect to settle your lawsuit? Again, the answer is: “It depends”. Some insurers view settlements as lump sum payments, without regard to how you allocate the settlement. For example, if they pay you $2,000,000, it may be up to you whether you apportion a part of the settlement to attorneys’ fees. Your position should be that to settle, you want $2,000,000 plus your attorneys’ fees. As you can see, attorneys’ fees are often part of the negotiation and are not something you should easily concede.
Before we get into ways to identify potential lawyers and law firms to handle your lawsuit, it is important to understand a fundamental underlying premise: there is no such thing as a good law firm or bad law firm. Every law firm has good lawyers and bad lawyers. What matters is which lawyers within the firm are handling your case. If I had a dollar for every time I have given this advice, we may not have had to sue our insurance carrier!
Based on the premise above, you should start your search by seeking out potential lawyers (as opposed to law firms). While you or somebody you know may already have a pre-existing relationship with a lawyer or law firm that they worked with on another legal matter, that doesn’t necessarily mean that they are the right lawyer to handle your homeowners’ lawsuit. Cousin Wendy’s lawyer might have done a great job with her divorce, and Uncle Mark’s lawyer may have been very helpful in setting up his will. However, just like you wouldn’t use a podiatrist if you needed brain surgery, the lawyer you are looking for has a very particular skillset.
Search engines (e.g. Google, Microsoft Edge) and AI agents (e.g. ChatGPT, Claude, Gemini, Manus) can be very helpful in identifying potential attorneys. Start with multiple searches/inquiries and compare the results. When you start to see the same attorneys coming up over and over again, add those names to your list of potential attorneys.
For example, you may start with: “list the largest judgments against homeowners’ insurance providers in California over the past 10 years and list the lawyers that represented the plaintiffs”. Or, “which plaintiffs’ attorneys in Los Angeles have filed lawsuits against homeowners’ insurance providers over the past 5 years”. If you are looking for an attorney that has experience bringing lawsuits against your particular insurance company, add that to the search. The idea is to do multiple searches and compare the results. Use your imagination. The goal is to do enough searches where the same names start coming up multiple times. There is not just one perfect search, you should conduct multiple searches.
Regardless of the type of fee arrangement you are seeking, you should always meet with and screen multiple attorneys. Meeting with a single attorney at only one law firm is one of the most common mistakes made by inexperienced potential clients. YOU NEED TO SHOP AROUND!!
Once you have narrowed down the list of names to two or three, you should reach out to your potential attorneys to set up meetings. Every attorney should agree to meet with you to discuss your potential lawsuit. Initial meetings are a professional courtesy and should be free. If any attorney tries to charge you for a first meeting, run (don’t walk) to the next name on your list.
While there should be no charge for the meeting, it is up to you to use both your and your potential attorney’s time wisely. You only make one first impression, and you should properly prepare for the meeting using the tools we outlined in our previous Chapters. By preparing the scrapbook, you should have some idea how you think you have been mistreated, including grounds for breach of contract and insurance bad faith. By comparing your policy limits to the actual cost to repair or rebuild your home, you should determine whether you may have a potential underinsurance claim.
While you are not expected to be a legal expert in these areas, you should take the time to at least preliminarily prepare the evidence discussed in the Chapters.
While it is not uncommon for meetings to occur via zoom or another video conference provider, my preference is for the first meeting to occur in person. In addition to the attorney that you reached out to, it is important that you meet with the entire legal team that will be working on your potential lawsuit, and for you to get a sense of the atmosphere of the offices. Is the office busy or is it empty because everybody works from home? Does everybody seem professional? This is an important decision and you not only want to meet the “chef”, you also want to meet the rest of the restaurant staff and tour the restaurant as well.
In addition to reviewing the potential facts of your lawsuit, you should also prepare a list of questions for the meeting. For example:
1. How many homeowners' policy lawsuits have you filed and what were the results?
2. Did any of your lawsuits include underinsurance claims?
3. Did any of the lawsuits go to trial?
4. How many jury trials have you completed in the last few years and what were the results?
5. How do you expect to staff this lawsuit?
6. Do you currently have any existing homeowners’ policy lawsuits?
7. If hourly – what is your hourly billing rate and the rates for the rest of the team that would work on the lawsuit? How much do you expect it will cost to prepare this lawsuit for trial?
8. If contingency – who will fund the costs in the case? Please explain the details of the contingency fee arrangement.
9. Can you describe any homeowners insurance cases that did not go well and what you learned from them?
You should ask just as many questions about an attorney's settlement experience as you do about trial experience. The reason for this will become apparent when you get to the ISMIC Series 2 Chapter called The Grand Performance. How does the attorney go about settling cases? Is there a settlement strategy from the beginning of the lawsuit, or is settlement something that only gets discussed when the other side raises it?
How does the attorney create settlement opportunities?
Ask about the attorney's philosophy on settlement overtures. Does the attorney believe that making the first settlement overture indicates weakness? If so, why? How does the attorney decide when the timing is right to make a demand, propose mediation, or otherwise open settlement discussions? Does the attorney use discovery, depositions, expert work, or motions strategically to help create settlement opportunities?
Ask for examples. How many homeowners insurance cases has the attorney settled? At what stage did those settlements occur? Did the attorney initiate the settlement discussions or did the insurance company? Has the attorney settled cases with your particular insurance company? How often does the attorney use mediation, and how does the attorney decide when a case is ready for mediation? Ask about cases that should have settled but did not, and what the attorney learned from them.
Finally, ask how settlement decisions are handled with the client. How are offers and counteroffers communicated? How does the attorney explain the risks and benefits of accepting or rejecting an offer? Who develops the settlement range and strategy? The decision whether to settle is ultimately yours. You want a lawyer who will give you candid advice, but who also understands that settlement is a process that should be planned and managed, not something that just happens.
The decision whether to settle is ultimately yours.
Regardless of whether you are pursuing an hourly or contingency arrangement, you should ask for two or three references (prior clients whose lawsuits were handled by the attorney).
Potential questions for the references:
1. Did the lawyer turn out to be the same person you met during the first interview?
2. Did anything about the lawyer or firm surprise you after you hired them?
3. How often did you speak with the attorney?
4. Were your calls and emails answered promptly?
5. Would you use the attorney/firm again?
6. What do you know now that you wish you knew before you hired the attorney/law firm?
7. How often were you updated on the status of the lawsuit?
8. Did the attorney take the time to answer your questions and address your concerns?
9. How did the attorney approach settlement negotiations?
10. Did you have the opportunity to provide input?
11. Were bills sent on time? Could you understand the bills? Were there any billing disputes?
If you decide to move forward, you will likely spend as much time talking and interacting with the attorney and team over the next year as you do with your family. Take your time and ask for a second meeting if necessary. Hiring an attorney should not be like “speed dating”. If the attorney does not take the time and make the effort to answer all of your questions, and give you the information and time that you need to feel comfortable with your decision, they are probably not the right fit for your lawsuit.
Before interviewing lawyers, first determine whether an hourly or contingency fee arrangement is financially realistic for your situation.
Attorney's fees and litigation costs are different. Make sure you understand who is responsible for paying litigation costs, when they must be paid, and how they affect your net recovery.
If you are considering a contingency fee arrangement, understand exactly how the contingency percentage is calculated and how litigation costs are handled before signing a fee agreement.
Your ability to finance a lawsuit may determine which law firms are realistic options. If you cannot afford an hourly fee arrangement, focus your search on firms that regularly handle contingency matters.
Look for lawyers with substantial experience handling homeowners insurance lawsuits, not simply lawyers with a good general reputation.
Use multiple sources, including search engines and AI tools, to identify attorneys whose names consistently appear in homeowners insurance litigation.
Prepare for your initial meeting. A lawyer can better evaluate your case if you have organized your documents, understand the basic facts, and can clearly explain what happened.
Interview more than one attorney. Ask thoughtful questions, meet the team that would be working on your case, and speak with former clients before making your decision.
Hiring a lawyer should be a deliberate decision, not a rushed one. Take the time to gather enough information to decide whether the attorney is the right fit for your lawsuit.
Ask about settlement experience as carefully as trial experience. Understand how the attorney creates settlement opportunities, approaches settlement overtures and mediation, and involves the client in settlement strategy and decisions.
In the first Series of Chapters, we covered the steps that you should take and topics you should consider in determining whether it makes sense to at least contact an attorney about a potential lawsuit against your homeowners’ insurance carrier. We also covered how to find and screen potential attorneys to handle your case. In Series 2, the Chapters will focus on what to expect after you select an attorney and law firm.