The economic realities.
In our Chapter entitled What Is I Sued My Insurance Company?, we stated that a lawsuit is a rigid process governed by facts, evidence, legal principles, and economics. The first seven Chapters of this series covered facts, evidence, and legal principles. The final two articles will focus on economics.
Although sometimes necessary, a lawsuit can be a very inefficient means of resolving a dispute. The party that initiates the lawsuit is asking a court to oversee a formal process for resolving the dispute. From the time the lawsuit is filed through trial, both sides are required to exchange certain information, develop their evidence and arguments, take depositions, retain experts when necessary, prepare and respond to motions, and ultimately prepare the case for trial. Doing that generally requires teams of highly skilled lawyers and, depending upon the issues, outside subject matter experts.
There are many other ways to resolve disputes that are faster, more efficient, and much less expensive.
There is an old adage that "everybody is entitled to their day in court." While the adage may sound good in theory, from a practical perspective, it simply isn't true. Almost anybody can file a lawsuit. There is no guarantee that the lawsuit will ever make it to trial. More importantly, unless the ends justify the means, meaning the likelihood of prevailing and the potential recovery are both high enough, it may make little economic sense to engage in such an inefficient and expensive process.
Let's assume that your insurance company has paid you almost everything you are entitled to receive under your policy, but you believe it still owes you another $50,000.
Let's also assume that you have done the work described in our previous articles. You have built your scrapbook and examined how your claim was handled. You don't appear to have a substantial insurance bad-faith claim. You have investigated whether you were underinsured and are satisfied that your policy limits were properly established. You have looked at your dwelling, personal property, and additional living expense coverages. After adding everything together, you conclude that the entire remaining dispute with your insurance company is $50,000.
Should you sue?
Probably not.
That doesn't mean the insurance company is right. It doesn't mean you aren't legally entitled to the $50,000. It simply means that spending hundreds of thousands of dollars pursuing $50,000 doesn't make economic sense.
Now change the number from $50,000 to $100,000.
The problem hasn't changed very much.
Now let's change the facts.
Assume that in addition to the $50,000 you believe you are still owed under the policy, it took your insurance company almost a year to pay the amounts it did pay, after delays that had nothing to do with you. And despite having extended replacement cost coverage, you have learned that it will cost another $2 million above your policy limits to repair or rebuild your home.
What initially appeared to be a $50,000 dispute may now include a potential $2 million underinsurance claim, as well as potential damages arising from the way your insurance claim was handled.
The economics look very different.
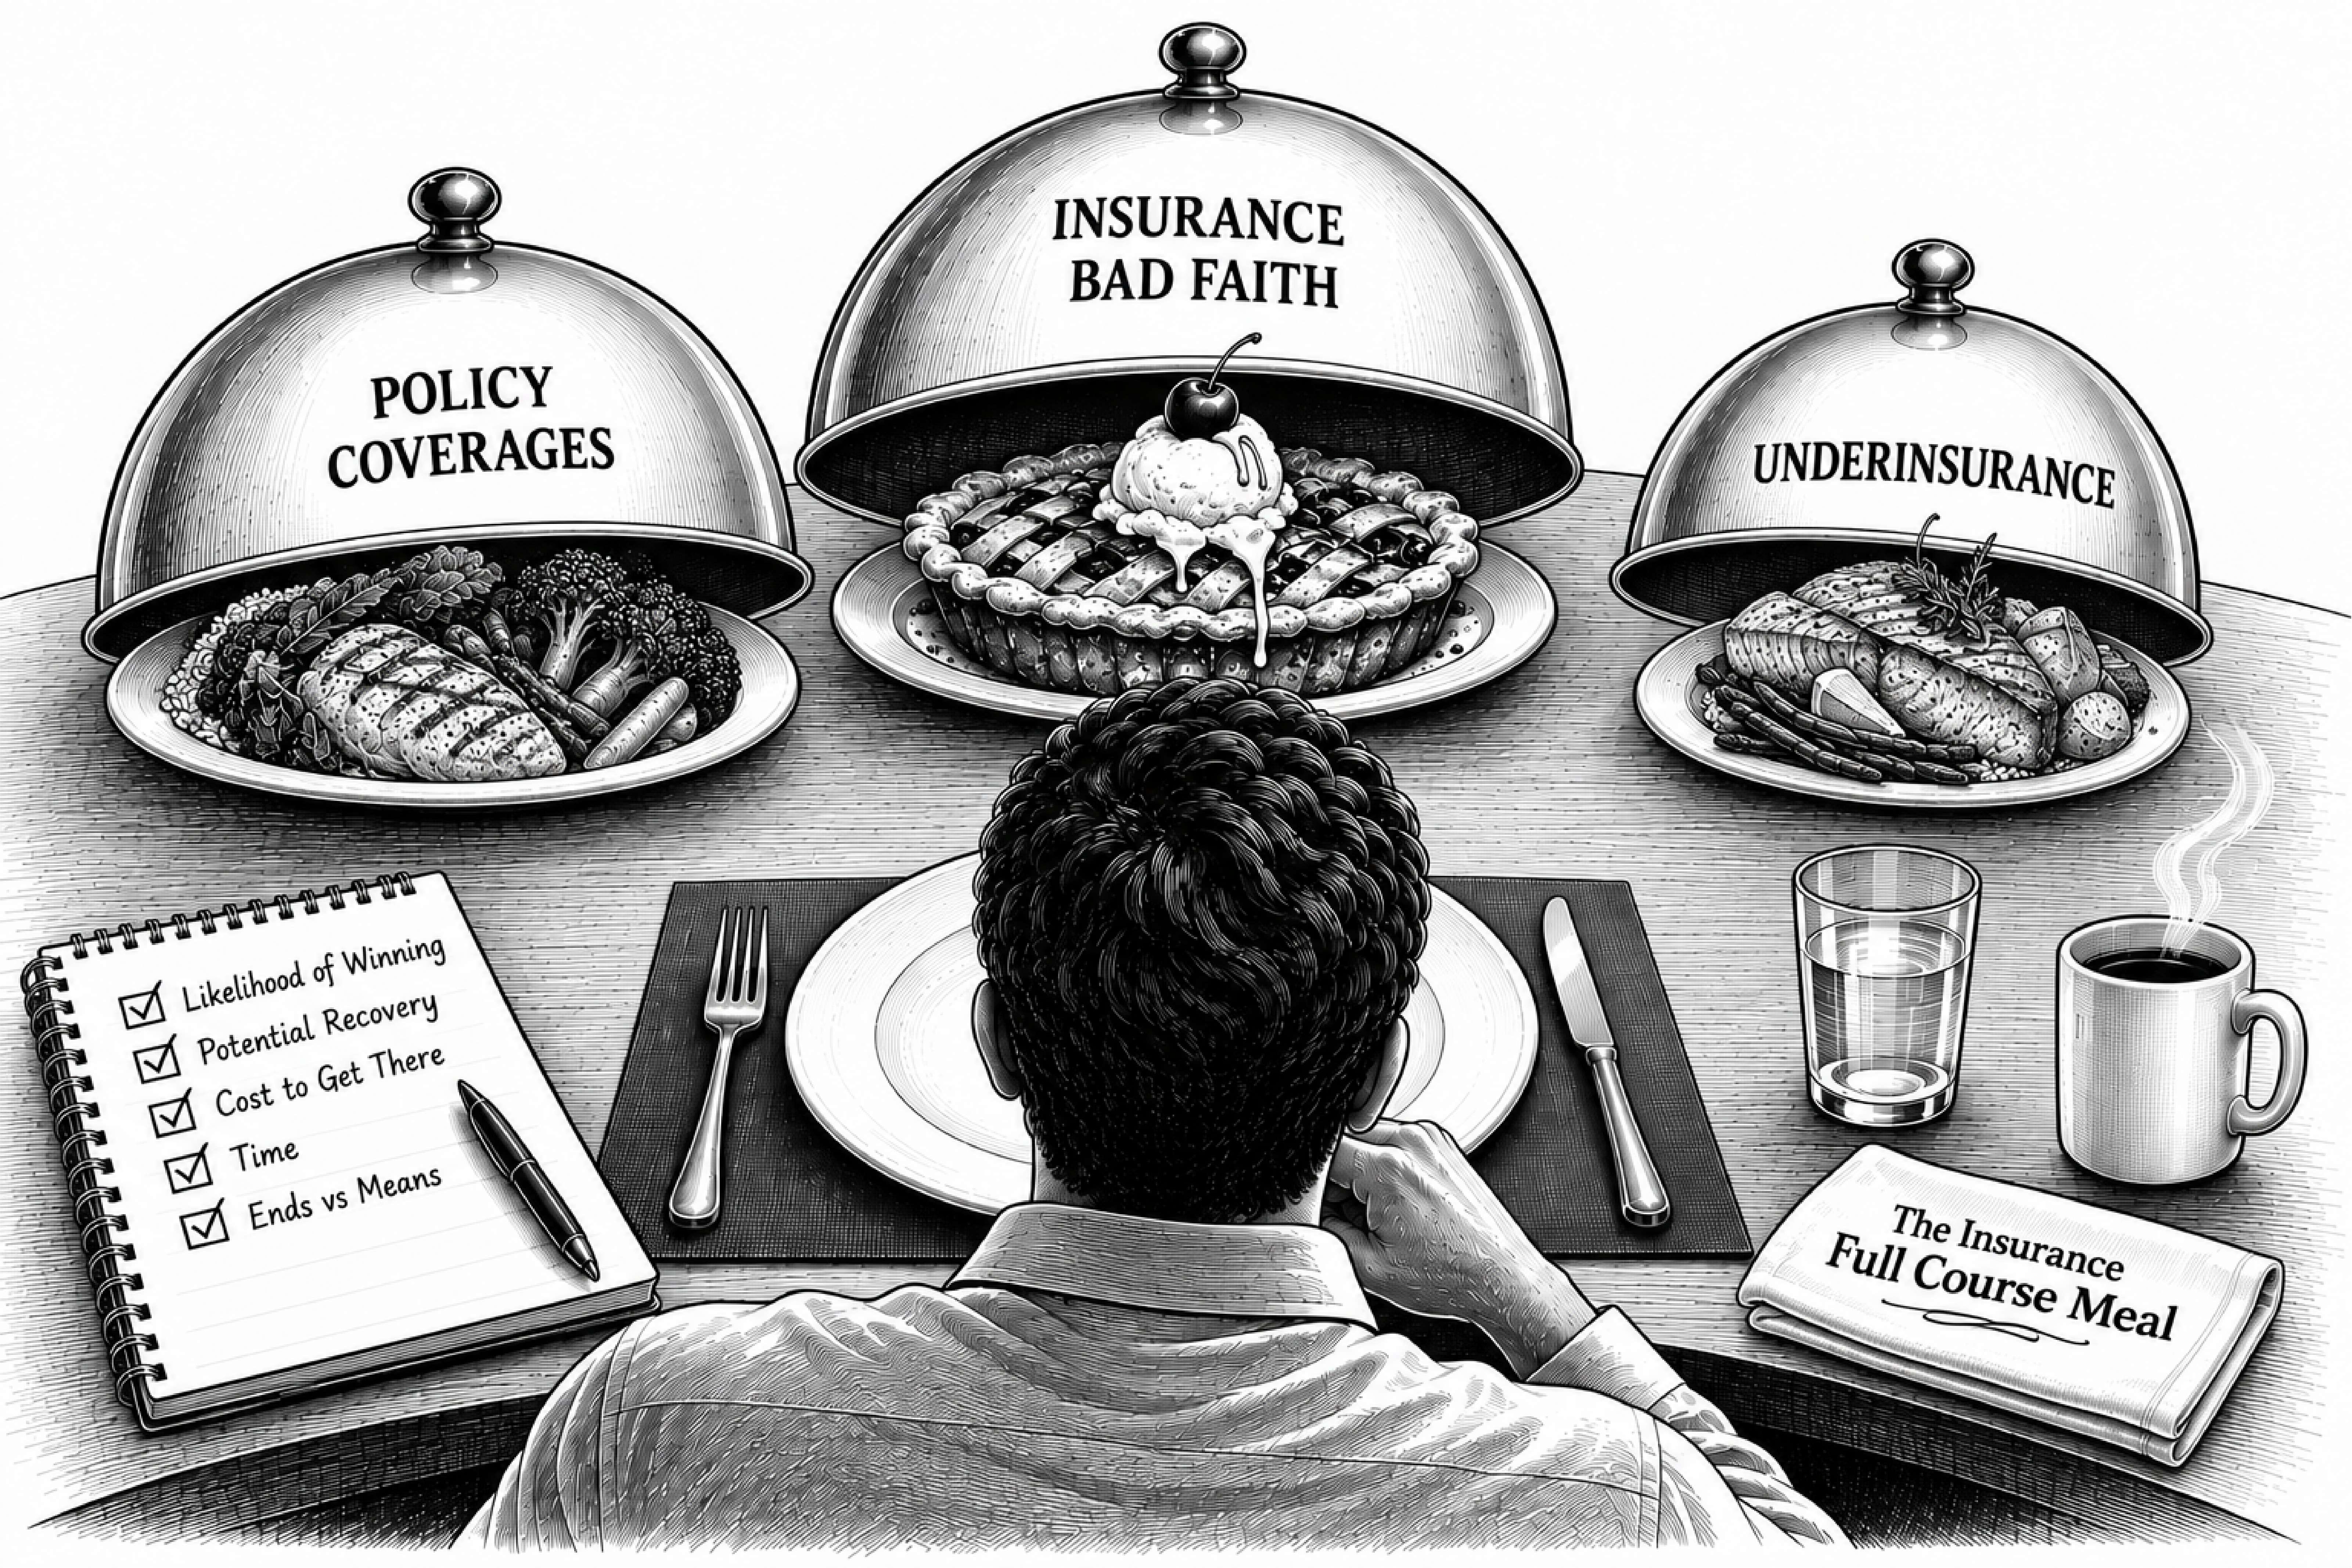
That is one reason we spent the previous several articles looking for all the food before asking whether there is enough.
The amount your insurance company has failed to pay under the policy is not necessarily the same as the potential value of your lawsuit.
When I managed lawsuits professionally, I never evaluated a case solely by asking how much we could recover if we won. The potential recovery was obviously important, but so were the likelihood of winning, what it would cost to get there, how long it would take, and what could happen along the way.
The same analysis applies to your insurance lawsuit.
Suppose you believe your insurance company owes you an additional $1 million. A $1 million dispute sounds substantial. But assume your lawyer tells you there are significant weaknesses in your case and estimates that you have only a 25% chance of prevailing.
Now assume instead that $500,000 is in dispute, the important facts are well documented, the applicable law appears favorable, and your lawyer believes the case is unusually strong.
Which lawsuit is worth more?
There isn't enough information to answer that question precisely. But the example demonstrates why the amount in dispute cannot be considered by itself.
The economic value of a lawsuit depends upon both the potential recovery and the likelihood of obtaining it.
And then you have to consider what it will cost to get there.
Based upon my experience, a complex homeowners insurance lawsuit handled by a law firm billing on an hourly basis can generate $500,000 to $1 million in attorney's fees before trial. Trial can add substantially more. Outside litigation costs, including expert witnesses, court reporters, deposition transcripts, document management, consultants, exhibits, and other expenses, can add tens or hundreds of thousands of dollars more.
Those numbers make the economics of a $50,000 dispute fairly easy to understand. You wouldn't knowingly spend $500,000 to collect $50,000.
But what if $500,000 is in dispute?
Would you spend $500,000 trying to recover $500,000?
Probably not.
What if $1 million is in dispute?
Now we need to know more.
How strong is the case? How much will it actually cost to pursue? Is there a reasonable possibility of settling early? Are there additional damages that may be recoverable? Is there a possibility of recovering some of your attorney's fees?
The larger the potential recovery becomes relative to the expected cost and risk of pursuing it, the more attractive the economics become.
How you pay your lawyers will also affect this calculation. If you pay your lawyers by the hour, you are paying the cost of their time as the lawsuit proceeds. If you seek a contingency arrangement, the law firm will make its own economic calculation before deciding whether to accept your case.
We will discuss both fee arrangements in the next Chapter.
I wish I could tell you that you should not consider filing a lawsuit unless at least $500,000, $1 million, or some other specific amount is at stake.
I can't.
The economics depend upon too many variables.
How much can you realistically recover? How strong is the evidence? What legal obstacles exist? How complicated will the lawsuit be? How many experts will be necessary? How much will the lawsuit cost? How long is it likely to take? Is there a realistic possibility of recovering attorney's fees? Is an early settlement reasonably possible?
Those questions are also why two experienced lawyers can look at the same lawsuit and reach different conclusions about its economic value.
There is no magic number.
But there is a minimum number for every lawsuit.
At some point, the potential recovery becomes too small, the likelihood of success too uncertain, or the cost of pursuing the lawsuit too great to justify proceeding. Where that point falls will be different for every lawsuit.
The important thing is to recognize that the point exists.
Attorney's fees and litigation costs aren't the only costs of a lawsuit.
Your time has value too.
No matter how good the lawyers you hire, you will be an indispensable part of your lawsuit. There will be documents to locate, facts to explain, decisions to make, meetings to attend, work from your lawyers to review, and eventually depositions and possibly a trial to prepare for.
You cannot simply turn your lawsuit over to a law firm and forget about it until a settlement check arrives.
In our next Series of Chapters, What to Expect, we will discuss what it means to become a good client and how you can participate productively in your lawsuit. For purposes of deciding whether to sue, however, the point is simpler.
Every hour you spend working on your lawsuit is an hour you cannot spend doing something else. After a catastrophic loss, that may mean time you could have spent with your family, working, relaxing, or rebuilding your life.
Nobody will send you a bill for that time.
That doesn't make it free.
There are many reasons you may want to sue your insurance company that have little to do with economics. Anger, revenge, fairness, justice, vindication, and a sense of right and wrong all come to mind.
Those emotions can be particularly strong in an insurance dispute because the insurance relationship was marketed to you as something personal.
Insurance companies spend enormous amounts of money telling us that they are good neighbors, that we are in good hands, and that they will be there when we need them. After paying premiums for years, it is easy to view the relationship in those terms.
The reality after a claim is very different.
To the insurance company, your claim is ultimately a business matter. Despite how personal the relationship may have seemed when the policy was sold to you, when it comes time to pay your claim, you are an actuarial calculation. A data point on a graph.
Decisions about how much to pay you, whether to deny all or part of your claim, how much to spend defending a lawsuit, and whether and for how much to settle are business decisions. They are made from a purely financial perspective.
Not based on what is right or wrong.
Despite how personal the insurance company's conduct may feel to you, to the insurance company it isn't personal. For the most part, it is strictly business.
That distinction becomes important when you decide whether to sue.
You need to bring some of the same cold economic discipline to that decision that the insurance company brings to its decisions about your claim. How much can you realistically recover? What are your chances of recovering it? What will it cost? How long will it take? How much of your own time will it consume?
That doesn't mean emotions have no place in a lawsuit. They do. The way an insurance company's conduct affected you may be an important part of your case and, depending upon the claims and evidence, may ultimately be important to a jury.
But emotion should not substitute for sound and economic realities when deciding whether to file the lawsuit in the first place.
If you need therapy to deal with the trauma of losing your home, possessions, or community, get therapy. If you need help dealing with anger toward your insurance company, get that help too. A lawsuit is an extraordinarily expensive and inefficient form of dispute resolution. It is an even worse form of therapy.
You may ultimately decide that vindication, justice, or principle is worth spending money to pursue. That is your decision. But make it knowingly.
Understand what the lawsuit may cost, what you can realistically recover, the likelihood of recovering it, and the amount of your own life it will consume.
Then decide whether the ends justify the means.
By this stage in the Series, you should have a much better idea of what may be included in your potential lawsuit.
You have looked at what the insurance company still owes under the policy. You have examined how the claim was handled. You have considered whether you were underinsured. You have looked at your personal property and ALE coverages. You have assembled the evidence that will help a lawyer evaluate those issues.
Now add up the meal.
Not every item you identify will necessarily be recoverable. Your lawyer will ultimately help you evaluate the strengths and weaknesses of the potential claims and what they may realistically be worth.
But before deciding to pursue a lawsuit, understand the distinction: Being right and having an economically viable lawsuit are not the same thing.
The legal system may provide a means to pursue what you are owed. Whether using that system makes economic sense is a different question.
There is no magic number. But there is a minimum number for every lawsuit.
In our next Chapter, Finding the Right Chef, we'll discuss hourly and contingency fee arrangements and how to find the right lawyer and law firm for your lawsuit.
A legitimate insurance claim is not necessarily an economically viable lawsuit.
The amount of unpaid policy benefits is not necessarily the potential value of your lawsuit. Look at the entire meal before deciding how much is really at stake.
The potential recovery cannot be evaluated by itself. The likelihood of obtaining that recovery, the expected legal fees and costs, and the time required to pursue it are also part of the calculation.
Lawsuits can be expensive and inefficient. A relatively small dispute may cost more to pursue than you could reasonably expect to recover.
Your own time is part of the cost of a lawsuit, even though nobody sends you a bill for it.
There is no universal minimum amount that makes a lawsuit worthwhile, but every lawsuit has an economic threshold.
Despite how personal the dispute may feel to you, to the insurance company it isn't personal. For the most part, it is strictly business. Bring the same cold economic discipline to your decision whether to sue.
A lawsuit is not therapy. If you decide to sue, the decision should be grounded primarily in the economic realities of the case, not anger, revenge, or a desire for vindication.
Before deciding how to pay for a lawsuit, first determine whether there is enough food on the table to justify pursuing it.