Why ALE coverage limits come-up short
In the previous two Chapters, we discussed the concept of underinsurance and how an understated Coverage A limit can have a cascading effect on other coverages within your homeowners' policy. Because Coverage B (personal property) and Coverage C (Additional Living Expense, or "ALE") are often calculated as percentages of the Coverage A limit, an artificially low Coverage A limit can reduce all three coverages at the same time.
The impact on personal property was the subject of our last Chapter. This Chapter focuses on Additional Living Expense coverage.
Most policyholders assume that if their home is destroyed, their homeowners' insurance will pay their additional living expenses until the home is repaired or rebuilt. After all, that is what "Additional Living Expense" coverage is designed to do.
Unfortunately, that assumption often turns out to be wrong.
Additional Living Expense coverage is intended to pay the increased costs you incur because your home is temporarily uninhabitable. Depending upon the policy, that may include rent for a temporary home, hotel bills, increased meal expenses, laundry, storage, additional transportation costs, and other reasonable expenses that would not have been incurred had the loss not occurred.
The problem is that rebuilding or remediating a home after a major wildfire rarely proceeds according to schedule. Debris must be removed. Plans must be prepared. Permits must be obtained. Contractors must be located. Materials become scarce. Labor costs increase. Building departments become overwhelmed.
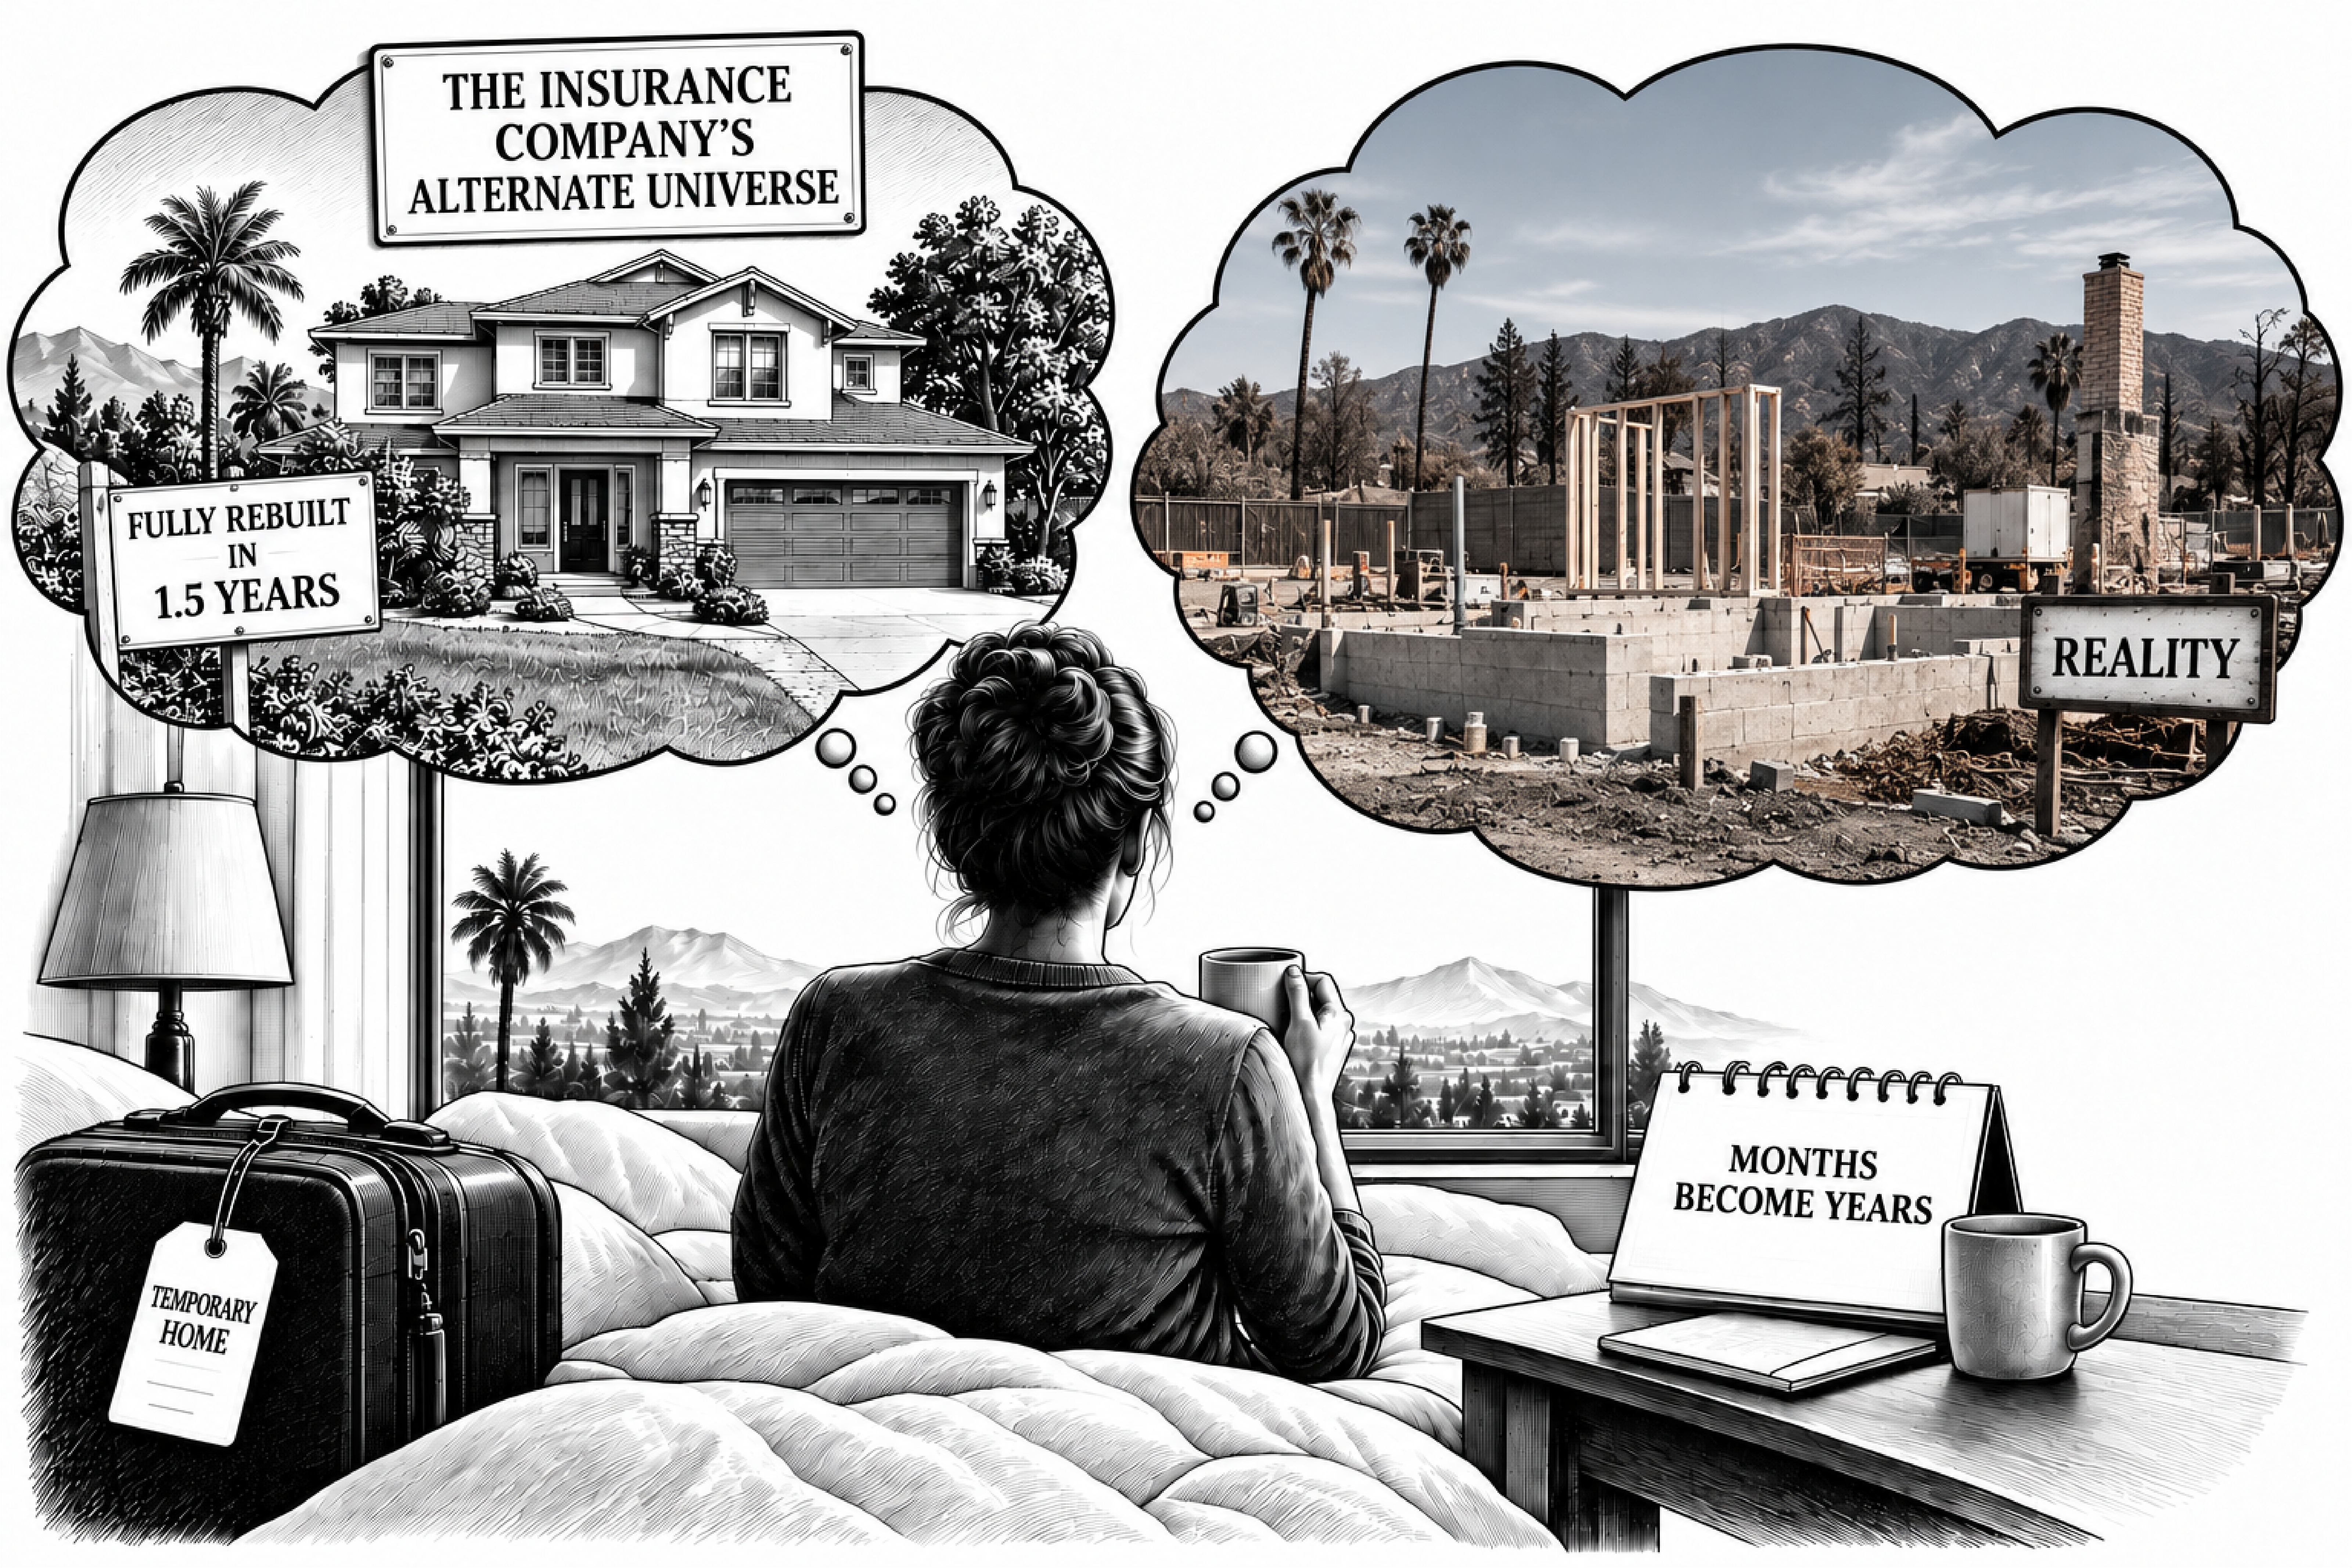
Months become years. Meanwhile, your additional living expenses continue every single month.
As discussed in the previous articles, Coverage C limits are frequently established as a percentage of the Coverage A dwelling limit. If your Coverage A limit was improperly set too low, there is a good chance that your Coverage C ALE limit was also set too low. The result is another example of the cascading effect of underinsurance. Even if your policy performs exactly as written, the available ALE benefits may simply not be enough to carry you through the time it actually takes or remediate to rebuild your home. As with underinsurance, the problem is that you may not discover the deficiency until after the loss, when it is too late.
Our assumption was that our policy would cover our actual additional living expenses while our home was being repaired or rebuilt. We did not discover until after the fire that, several years earlier, our policy had been changed to provide a fixed dollar amount of ALE coverage instead of the actual alternative living expenses that we incurred. Like many policyholders, we never noticed the change.
California insurance regulations require insurers to provide specific notice before certain reductions or changes in policy coverage become effective. It is worth checking whether your ALE coverage changed over the past years, and if so, discuss with your attorney whether the changes were properly noticed and disclosed.
While some insurance companies limit ALE by a fixed dollar amount, others limit coverage by time. In either case, it seems that ALE coverage limits are often insufficient to accomplish its purpose, to cover expenses until the policyholrs. While policy holders usually focus on their dwelling coverage because that is usually the largest number shown on the declarations page, much less attention is paid to changes affecting the other coverages in the policy. Those changes may not seem important during a routine annual renewal. They can become very important after a total loss.
nsurance companies also have a duty to investigate, evaluate, and pay covered claims reasonably and without unnecessary delay. A policyholder forced to wait weeks or months for reimbursement of legitimate housing expenses may experience housing insecurity and financial hardship at precisely the time the coverage was intended to prevent it. Depending upon the facts, unreasonable delays or failures to pay ALE benefits may become evidence supporting insurance bad faith and other bases for a homeowners' policy lawsuit.
As with personal property coverage, ALE is another example of why underinsurance can have consequences extending far beyond the cost of rebuilding the house itself. If your Additional Living Expense benefits are exhausted months before your home is ready to occupy, your financial burden does not disappear. The rent continues. The mortgage may continue. Life continues.
Only the insurance benefits stop.
The purpose of Additional Living Expense benefits is to last until your home is ready for re-occupancy. If your ALE is used up before your home is ready, it may be a cascading effect of you being underinsured. Insufficient ALE coverage can also be caused if, at the time you purchased your policy or at renewal, your insurance company underestimated the time it would take to repair or rebuild your home, especially after a widespread disaster. It is also worth considering whether your insurance company was reasonable in estimating the time that it would take to repair or rebuild your home. These and other potential causes of insufficient ALE coverage should be explored with your attorney, if you elect to file a lawsuit. Too often, the issue is whether your insurance company can also be at fault, so you may be living in an alternative universe.
Additional Living Expense (ALE) coverage often ends long before a home is repaired, remediated, or rebuilt. Many policyholders assume ALE benefits will continue until they return home. Depending on the policy, that assumption may be incorrect.
An understated Coverage A limit can also reduce your ALE coverage. Because ALE limits are often calculated as a percentage of Coverage A, underinsurance can have a cascading effect on the amount available for temporary living expenses.
Review your policy for changes to ALE coverage. Some insurers provide a fixed dollar amount, while others limit coverage by time. If your ALE coverage changed, discuss with your attorney whether the required notices and disclosures were provided.
Delayed or unreasonable ALE payments may have legal significance. Depending on the facts, an insurer's failure to timely pay covered ALE benefits may become evidence supporting insurance bad faith and other claims asserted in a homeowners' policy lawsuit.