How to calculate the filing deadline for your potential lawsuit
If you are involved in a dispute with your homeowners insurance company and are considering legal action, one of the first questions you should answer is:
The answer is not always as simple as identifying the date of the fire. California law, your insurance policy, and the way your claim has been handled may all affect the filing deadline.
Understanding that deadline is important because failing to file suit on time can permanently bar an otherwise valid claim.
Most California homeowners insurance policies require lawsuits seeking benefits under the policy to be filed within one year after the date of the loss.
California law modifies that rule in two important ways.
When a covered loss is related to a declared state of emergency, California law generally extends the contractual filing deadline from one year to two years after the date of the loss.
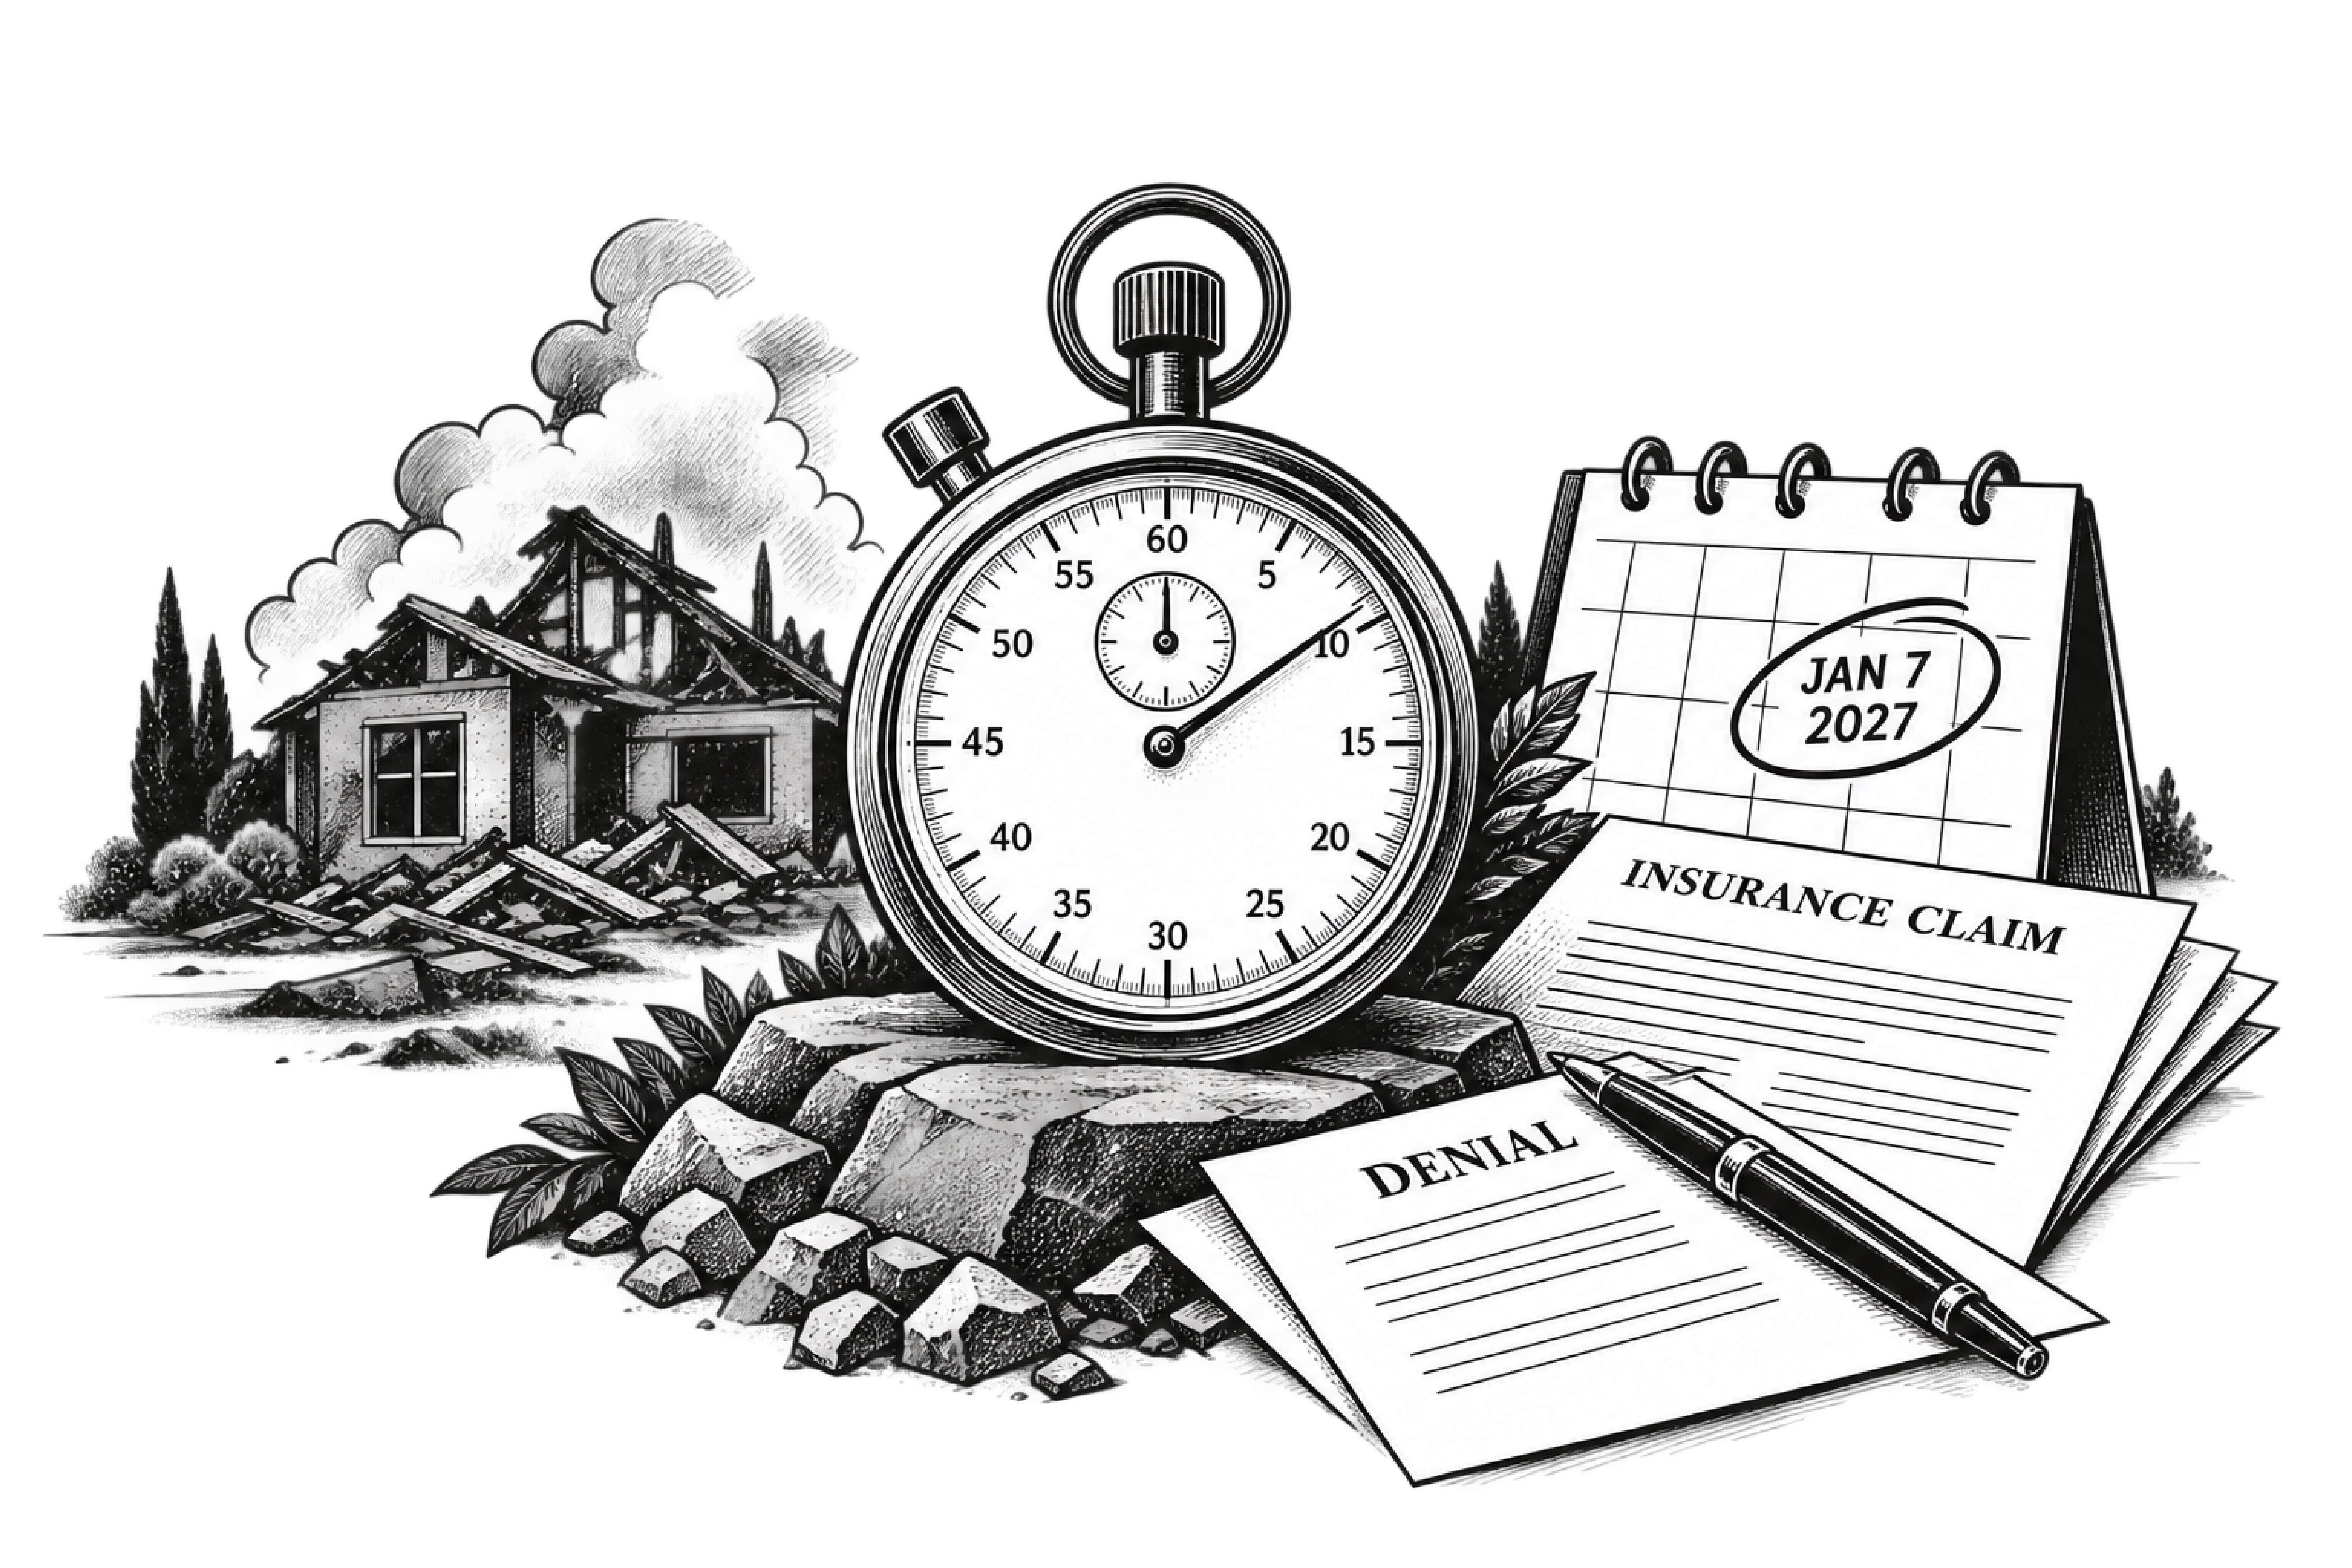
Because Governor Gavin Newsom declared a state of emergency on January 7, 2025, in response to the Los Angeles wildfires, many lawsuits seeking benefits under homeowners insurancepolicies arising from those fires will have an initial filing deadline of January 7, 2027.
California law also generally pauses the filing deadline while your insurance company is actively evaluating your claim.
Lawyers refer to this as equitable tolling, but the concept is easier to understand with a simple analogy.
Imagine the filing deadline is a stopwatch.
The stopwatch starts running on the date of the loss.
When you timely report your claim, the stopwatch generally pauses while the insurance company investigates and evaluates the claim.
During that pause, the insurer may inspect the property, review estimates, obtain expert reports, request additional information, and determine what benefits are owed under the policy.
When the insurance company issues an unequivocal written denial of all or part of your claim, the stopwatch generally begins running again.
Once the stopwatch resumes, the remaining time continues to run until the filing deadline expires.
The purpose of this rule is straightforward. A policyholder should not have to file a lawsuit while the insurance company is still deciding whether benefits are owed.
Not every letter from an insurance company restarts the stopwatch.
Whether a communication constitutes an unequivocal written denial depends on its language and the surrounding circumstances.
A clear written denial of coverage generally restarts the filing deadline.
A request for additional information generally does not.
A letter stating that the insurer is continuing to investigate generally does not.
A partial denial may restart the deadline for the issues that have been finally decided while other portions of the claim remain under review.
Likewise, ongoing settlement discussions or an adjuster's statement that the company will "take another look" generally should not be assumed to pause the filing deadline again after a written denial has been issued.
Determining whether a communication constitutes an unequivocal written denial can depend on the facts of a particular claim.
Assume the following timeline:
January 7, 2025
Wildfire damages your home
The stopwatch starts.
Seven days pass.
January 14, 2025
You report your claim.
The stopwatch pauses.
During the next 208 days, the insurance company investigates the claim.
The insurer inspects the property, reviews estimates, evaluates coverage, and determines what benefits may be owed.
August 10, 2025
The insurance company issues an unequivocal written denial.
The stopwatch begins running again.
Because only seven days had elapsed before the claim was reported, nearly the entire filing period remains. The 208 days during which the claim was under review are generally added to the filing deadline.
As a practical matter, if there is a possibility that litigation may become necessary, it is generally prudent to begin evaluating your options well before the two-year anniversary of the loss. For the January 7, 2025 Los Angeles wildfires, that date is January 7, 2027.
The actual filing deadline may ultimately be later if the deadline was paused while the insurance company evaluated the claim. Determining that deadline, however, often requires reviewing the insurance policy, the insurer's written communications, and the chronology of the claim.
Selecting an attorney, evaluating potential legal claims, gathering records, consulting experts, and preparing a lawsuit all take time. Waiting until the final weeks before the applicable deadline may unnecessarily limit your options.
A homeowners insurance claim often consists of several separate components, including the dwelling, personal property, additional living expenses, landscaping, debris removal, and other coverages.
It is not uncommon for an insurance company to complete its investigation of one portion of a claim while continuing to investigate another.
Questions can therefore arise as to whether different portions of a claim may have different filing deadlines depending on what has been finally resolved and what remains under investigation.
California appellate courts have not squarely addressed every possible situation, making these issues highly fact-specific.
For that reason, homeowners should avoid assuming that every dispute under the policy necessarily shares the same filing deadline.
One of the most useful things you can do before consulting an attorney is to prepare a detailed timeline of your insurance claim.
The timeline should identify significant events such as when the claim was reported, inspections occurred, payments were made, requests for information were received, coverage decisions were issued, and other important communications took place.
A well-prepared timeline can help identify issues affecting the filing deadline and will likely be one of the first documents an attorney asks to review.
Lawsuits seeking benefits under homeowners insurance policies are subject to filing deadlines.
For many claims arising from the January 2025 Los Angeles wildfires, California law generally extends the initial contractual deadline from one year to two years after the loss.
Think of the filing deadline as a stopwatch that starts and stops.
The filing deadline is generally paused while the insurance company is actively evaluating the claim and resumes when the insurer issues an unequivocal written denial.
Determining the actual filing deadline is akin to calculating for how many days the stopwatch has been running.
If litigation is a possibility, begin evaluating your options well before January 7, 2027.